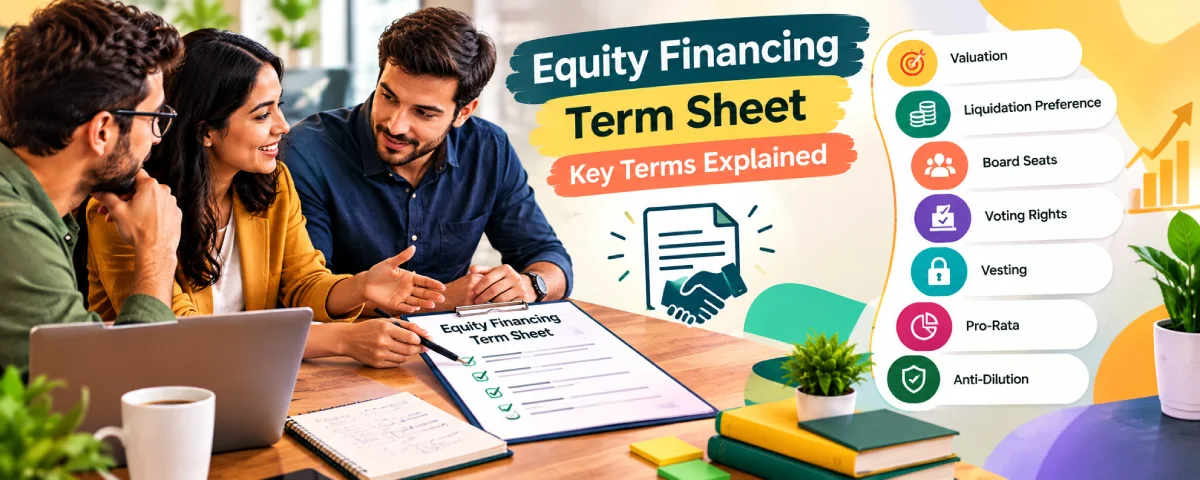
Equity Financing Term Sheet: Key Terms Explained
Where to begin: Start with the main Equity Financing pillar guide first. Then use this focused guide to understand the key terms that appear in equity financing term sheets and what they mean for founders.
A term sheet is the short document that outlines the main economic and control terms of an investment before the full legal paperwork is drafted. It is usually non-binding except for a few clauses, yet it sets the framework for everything that follows. In 2026 most early-stage and growth equity deals still begin with a term sheet, and the difference between a standard set of terms and an aggressive one can be worth millions of dollars and real control over the company.
This guide explains what a term sheet is and which parts may be binding, how valuation and liquidation preferences work, what board seats and voting rights actually control, how vesting, pro-rata, and anti-dilution terms differ, and which clauses deserve professional review before you sign. The language stays practical so you can recognise standard market terms and spot the ones that need negotiation.
What is a term sheet and which parts may be binding?
A term sheet is a summary of the proposed deal. It is typically 5–15 pages and covers the price, the type of security, the main investor rights, and the governance structure. Most of the document is non-binding. That means either side can still walk away. However, two or three clauses are often made binding from the moment the term sheet is signed:
- Confidentiality – neither side can share the terms or the existence of the discussions.
- Exclusivity / no-shop – the company agrees not to solicit or negotiate with other investors for a set period (commonly 30–60 days).
- Sometimes expense reimbursement – the company agrees to pay the investor’s legal fees if the deal closes, or in some cases even if it does not.
Everything else – valuation, liquidation preference, board seats, etc. – is a statement of intent. The final, binding terms appear later in the stock purchase agreement, investor rights agreement, and related documents.
Because the term sheet shapes the later legal documents, treating it as “just a non-binding summary” is risky. Once the main points are agreed, changing them becomes harder and more expensive.
How do valuation and liquidation preferences work?
Valuation sets the price of the round. It is usually expressed as a pre-money valuation. The post-money valuation equals pre-money plus the new investment. Investor ownership is calculated from the post-money figure. Option-pool requirements can change the effective economics, so the headline valuation alone never tells the full story.
Liquidation preference determines who gets paid first, and how much, when the company is sold, merged, or wound up. This is often more important than valuation in ordinary (non-unicorn) exits.
The market-standard term in 2026 for most early-stage deals is 1x non-participating preferred:
- The investor receives the first money out equal to their original investment (1x).
- After that, they convert into common shares and share the remaining proceeds pro-rata with everyone else.
- If the pro-rata share would be higher than the 1x preference, they simply take the higher amount.
Participating preferred is more investor-friendly. The investor takes their 1x (or higher) preference and then also participates in the remaining proceeds. This can significantly reduce the amount left for common shareholders in a moderate exit.
Higher multiples (2x or 3x) or uncapped participating preferences are generally considered aggressive and should be negotiated down in most situations.
What do board seats and voting rights control?
Board composition decides who governs the company on a day-to-day strategic level. A typical early-stage structure after a priced round is:
- Two seats elected by the common shareholders (usually the founders)
- One seat elected by the lead investor
- Sometimes one independent seat mutually agreed
At Series A and later the board often expands to five seats (two common, two investor, one independent). Control of the board matters because many important decisions require board approval: hiring or firing the CEO, approving large budgets, raising more capital, selling the company, etc.
Protective provisions (also called veto rights) give preferred investors the right to block certain actions even if they do not control the board. Common protective provisions cover:
- Selling the company or substantially all assets
- Issuing new shares senior to or on parity with the existing preferred
- Changing the certificate of incorporation or bylaws in ways that affect preferred rights
- Large debt or related-party transactions
- Changing the size of the board
These rights are normal. The question is how long the list is and how tightly the thresholds are drafted. An overly long list of vetoes can slow decision-making.
How do vesting, pro rata, and anti-dilution terms differ?
Founder vesting
Even after a financing, investors often require that founder shares continue to vest (or re-vest) over time, commonly four years with a one-year cliff. The purpose is to keep founders committed. Single-trigger or double-trigger acceleration on a change of control is frequently negotiated.
Pro-rata rights
These give existing investors the right to invest in future rounds in order to maintain their ownership percentage. Pro-rata rights are standard and generally founder-friendly because they help bring experienced capital into later rounds. Super pro-rata (the right to buy more than the current percentage) is more aggressive and should be limited.
Anti-dilution protection
This protects investors if the company later raises money at a lower price per share (a down round). There are two main forms:
- Broad-based weighted average – the market standard. It adjusts the conversion price using a formula that takes into account both the size and the price of the down round. The dilution is shared.
- Full ratchet – the investor’s conversion price is reduced all the way to the new lower price, regardless of how small the down round is. This is much more punitive for founders and common shareholders and is rarely accepted in standard deals.
Most term sheets in 2026 use broad-based weighted average anti-dilution.
Which terms need professional review before signing?
Almost every clause benefits from experienced counsel, but these deserve particular attention:
- Liquidation preference (multiple and participating vs non-participating)
- Board composition and protective provisions
- Option-pool size and whether it is pre-money or post-money
- Anti-dilution type
- Founder vesting and acceleration
- Any redemption rights or cumulative dividends (uncommon and usually unfavourable)
- Drag-along and tag-along rights
- Information and registration rights
- Exclusivity period length and expense reimbursement
A good startup lawyer will flag non-standard language, explain the practical consequences, and help you prioritise which points are worth negotiating. Trying to interpret a term sheet without counsel is one of the most expensive shortcuts a founder can take.
Practical comparison of standard vs aggressive terms (2026)
| Term | Standard / Founder-Friendly | More Aggressive / Investor-Heavy |
| Liquidation preference | 1x non-participating | 1x+ participating or 2x+ |
| Anti-dilution | Broad-based weighted average | Full ratchet |
| Board | Founders retain influence or control | Investor majority |
| Option pool | 10–15%, clearly defined timing | Large pool created pre-money |
| Founder vesting | Standard 4-year with acceleration | Long re-vesting, limited acceleration |
| Protective provisions | Reasonable list | Very long list of vetoes |
Common mistakes founders make with term sheets
- Focusing only on valuation and ignoring liquidation preference and board control
- Accepting a large pre-money option pool without modelling the ownership impact
- Agreeing to full-ratchet anti-dilution or participating preferred without understanding the downside
- Signing a long exclusivity period that blocks other conversations
- Treating the term sheet as non-binding in spirit and therefore not negotiating hard enough
- Skipping legal review because “it looks standard”
Troubleshooting
The term sheet has a high valuation but aggressive other terms.
Model the full economic outcome under different exit scenarios. A lower valuation with clean 1x non-participating terms is often better than a higher valuation with participating preferred.
I do not understand a clause.
Ask for a plain-English explanation from the investor and then confirm with your own lawyer. Never assume.
Multiple term sheets arrive with different structures.
Create a side-by-side comparison of the five or six most important terms, not just the pre-money number. Speak with founders who have worked with each firm.
The exclusivity period feels too long.
Negotiate it down. 30–45 days is common; longer periods need strong justification.
Frequently Asked Questions
Is a term sheet legally binding?
Most of it is not. Confidentiality, exclusivity, and sometimes expense provisions usually are binding. The economic and control terms become binding only when the definitive agreements are signed.
How long does it take from term sheet to closing?
Typically 4–8 weeks if diligence and documentation go smoothly. Complicated issues or busy lawyers can extend the timeline.
Can I negotiate after signing the term sheet?
Small clarifications are common. Major changes to economics or control become difficult and can damage trust.
What is the difference between a term sheet and a SAFE?
A SAFE is itself an investment instrument. A term sheet outlines the terms of a priced equity round that will later be documented in full legal agreements.
Do I need a lawyer for a small angel round?
Even for smaller rounds, having counsel review the documents is wise. The cost is usually far lower than the cost of a poorly structured deal.
Conclusion
A term sheet is more than a price tag. It sets the economic waterfall, the governance structure, and the ongoing rights of the investors. The standard package in 2026 — reasonable valuation, 1x non-participating preference, broad-based weighted-average anti-dilution, balanced board, and a clearly defined option pool — leaves room for both sides to win. Departures from that package should be deliberate and well understood.
Read every clause, model the ownership and exit consequences, and have experienced counsel review the document before you sign. The hour or two spent understanding the term sheet can protect years of future ownership and control.
Return to the main Equity Financing pillar page for the full overview. When you need more detail on angels, venture capital process, dilution, valuation mechanics, or equity versus debt, move to the relevant cluster guides. Clear term-sheet literacy is one of the highest-leverage skills a founder can develop before accepting institutional capital.