Pre-Money vs Post-Money Valuation Explained
Where to begin: Start with the main Equity Financing pillar guide first. Then use this focused guide to understand the difference between pre-money and post-money valuation and how the numbers actually affect your ownership.
Valuation is one of the first numbers founders and investors discuss, yet it is also one of the most commonly misunderstood. The difference between pre-money and post-money valuation determines exactly how much of the company the new investors will own and how much dilution existing shareholders will experience. Getting the framing wrong can quietly cost founders several percentage points of ownership.
This guide explains what pre-money valuation means, what post-money valuation means, how investment amount and ownership are linked, how option pools change the real numbers, and the most common mistakes founders make. Everything is shown with clear examples so you can apply the same logic to your own term sheet discussions.
What is pre-money valuation?
Pre-money valuation is the agreed value of the company before the new investment money is added. It is the price tag placed on the existing business and all of its current shareholders.
When someone says “we are investing at a $10 million pre-money,” they mean the company is worth $10 million today, before their cash goes in. The new money is then added on top of that figure.
Pre-money valuation is the number that is usually negotiated hardest. It reflects the company’s traction, team, market opportunity, competitive position, and the supply and demand of capital at that moment. In 2026, pre-money valuations vary widely by sector and stage, with artificial intelligence companies often commanding higher figures than many other categories.
What is post-money valuation?
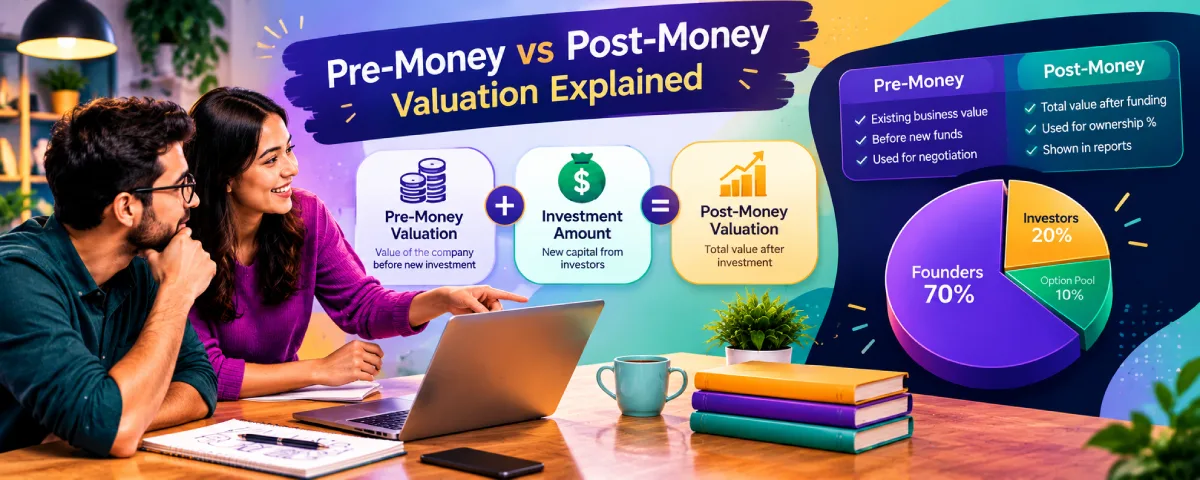
Post-money valuation is simply the pre-money valuation plus the new investment amount.
Post-money = Pre-money + Investment
If the pre-money is $10 million and the investor puts in $2.5 million, the post-money valuation is $12.5 million.
Post-money valuation is the number used to calculate the new investor’s ownership percentage. It is also the valuation that appears in many public reports and databases after a round closes.
How are investment amount and ownership related?
Investor ownership is always calculated against the post-money valuation:
Investor ownership % = Investment amount ÷ Post-money valuation
This is the single most important formula in early-stage fundraising.
Example 1 – Clear pre-money framing
Pre-money: $8 million
Investment: $2 million
Post-money: $10 million
Investor owns: $2 million ÷ $10 million = 20%
Founders and existing shareholders keep: 80%
Example 2 – Same numbers, different framing
If someone says “$2 million at a $10 million valuation” without specifying pre or post, the ownership outcome changes:
- If $10 million is pre-money → post-money is $12 million → investor owns 16.7%
- If $10 million is post-money → pre-money is $8 million → investor owns 20%
The difference of 3.3 percentage points is real ownership. At a later $100 million exit, that gap is worth $3.3 million. Always clarify whether a quoted valuation is pre-money or post-money.
How do option pools change the calculation?
The employee option pool is where many founders lose ownership without realising it. Investors almost always require a pool of shares reserved for future employees (commonly 10–20% of the fully diluted company after the round). The critical detail is whether that pool is created or expanded on a pre-money or post-money basis.
In the large majority of term sheets the pool is set on a pre-money basis. That means the dilution from creating or increasing the pool falls entirely on the founders and existing shareholders. The new investors do not share that dilution.
Worked example of the option-pool effect
Stated terms: $5 million investment at $20 million pre-money, with a requirement for a 15% post-round option pool. Current pool is only 5%.
Headline view (what many founders first think):
Pre-money $20 million + $5 million = $25 million post-money
Investor owns 20%
Existing shareholders own 80%
Real outcome after pre-money pool top-up:
The company must create additional pool shares so that the total pool equals 15% of the post-money company. Those new pool shares are issued before the investor’s money is counted. The effective value of the existing shareholders’ stake is reduced. The investor still receives their full 20% of the final company, while founders absorb both the investor dilution and the pool dilution.
In practice the effective pre-money valuation for existing shareholders is often several million dollars lower than the headline number. A 10–15% pool top-up on a pre-money basis can easily cost founders 5–8 extra percentage points of ownership compared with a true post-money pool treatment.
Always ask two questions:
- What size option pool is required after the round?
- Is that pool calculated on a pre-money or post-money basis?
Model both scenarios before you agree to the term sheet.
What valuation mistakes should founders avoid?
Mistake 1 – Assuming every quoted number is pre-money
Many conversations use the word “valuation” without the pre/post qualifier. Confirm the framing in writing.
Mistake 2 – Ignoring the option-pool shuffle
A high headline pre-money with a large pre-money pool can be worse for founders than a slightly lower pre-money with a smaller or post-money pool.
Mistake 3 – Forgetting converting SAFEs and notes
Outstanding SAFEs and convertible notes convert into shares and take ownership before or alongside the new priced round. Always model the fully diluted picture after conversion.
Mistake 4 – Focusing only on the pre-money number
The combination of pre-money, investment amount, pool size, and pool timing determines the real ownership outcome. Optimising one variable while ignoring the others leads to surprises.
Mistake 5 – Not running the numbers yourself
Never rely solely on the investor’s or lawyer’s summary. Build a simple spreadsheet that shows pre-money, investment, post-money, pool, and resulting ownership percentages for every major shareholder group.
Mistake 6 – Comparing valuations across very different stages or sectors
A $15 million pre-money for a pre-revenue company is not the same as a $15 million pre-money for a company with $2 million in annual recurring revenue. Context matters.
Practical steps before you negotiate valuation
- Decide your target raise amount and the minimum ownership you are willing to retain after the round.
- Build a simple model that includes the current option pool and any outstanding SAFEs or notes.
- Calculate the ownership outcome under different pre-money assumptions.
- Explicitly model the impact of a 10%, 15%, and 20% option pool on both pre-money and post-money bases.
- Prepare to discuss the full package (valuation + pool + other terms) rather than a single number.
- Get the final numbers written into the term sheet with clear pre/post language and pool treatment.
Side-by-side comparison table
| Scenario | Pre-Money | Investment | Post-Money | Investor % | Notes |
| Clean pre-money | $10M | $2.5M | $12.5M | 20% | No pool change |
| Same numbers called post-money | $7.5M | $2.5M | $10M | 25% | Founders give up more |
| $10M pre + 15% pre-money pool | $10M | $2.5M | $12.5M | ~20% | Founders absorb pool dilution |
| $10M pre + 15% post-money pool | $10M | $2.5M | $12.5M | ~17% | Dilution shared more evenly |
(The exact percentages shift slightly once the precise share counts are calculated, but the direction of the effect is consistent.)
Troubleshooting common situations
The investor says “$X million valuation” without pre or post.
Ask for clarification immediately and confirm in writing: “Just to confirm, is that a $X million pre-money valuation?”
The term sheet shows a high pre-money but a large pool.
Run the effective pre-money calculation. Decide whether the headline number is still attractive after the pool impact.
I have several SAFEs with different caps.
Convert each SAFE to its ownership percentage first, sum them, then layer the new priced round and pool on top.
I am not sure what a fair pre-money is.
Look at recent comparable rounds in your sector and stage, adjust for your specific traction, and test a range of outcomes in your model rather than anchoring on a single number.
Frequently Asked Questions
Is a higher pre-money always better?
Not if it comes with a much larger pre-money option pool or other unfavourable terms. Look at the full ownership outcome.
Why do investors prefer pre-money pool treatment?
It protects their ownership percentage. The dilution from the pool is borne by existing shareholders.
Can I negotiate a post-money option pool?
It is possible but less common. Strong traction and competitive interest improve your ability to negotiate pool timing and size.
Does post-money valuation include the option pool?
The post-money valuation is pre-money plus cash invested. The option pool affects how that value is divided among shareholders, not the headline post-money number itself.
How do I explain the difference to a co-founder or advisor?
Use the simple formula: Post-money = Pre-money + Investment. Investor ownership = Investment ÷ Post-money. Then show the extra effect of a pre-money pool with a short numerical example.
Conclusion
Pre-money valuation is the value of the company before new money arrives. Post-money valuation is that value plus the new money. Investor ownership is always calculated from the post-money figure. The option pool, especially when created on a pre-money basis, can significantly change the real dilution founders experience.
The difference between a clean understanding of these numbers and a vague one is often several percentage points of ownership — money that compounds over the life of the company. Run the arithmetic yourself, clarify every term in writing, and negotiate the full package rather than a single headline number.
Return to the main Equity Financing pillar page for the complete overview. When you need more detail on angels, venture capital process, dilution mechanics, term sheets, or equity versus debt, move to the relevant cluster guides. Clear valuation math is one of the highest-leverage skills a founder can develop before walking into any term-sheet conversation.