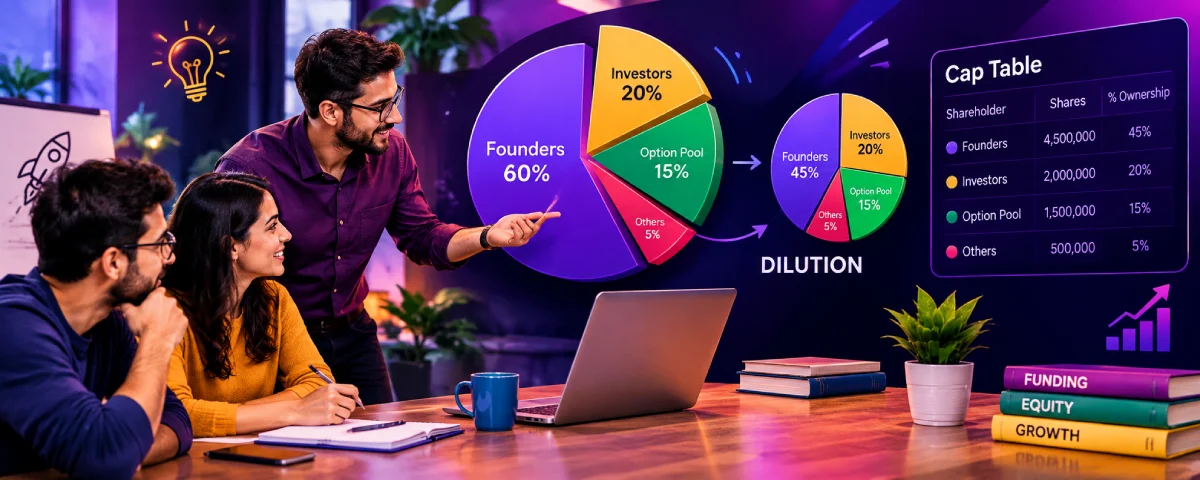
Where to begin: Start with the main Equity Financing pillar guide first. Then, use this targeted guide to help you see how the percentage of ownership will change when you raise money. The concept of equity dilution is an important but often-misunderstood area in early stage financing. Every time a business raises capital by issuing stock, the percentage of ownership of the existing investors will be diluted
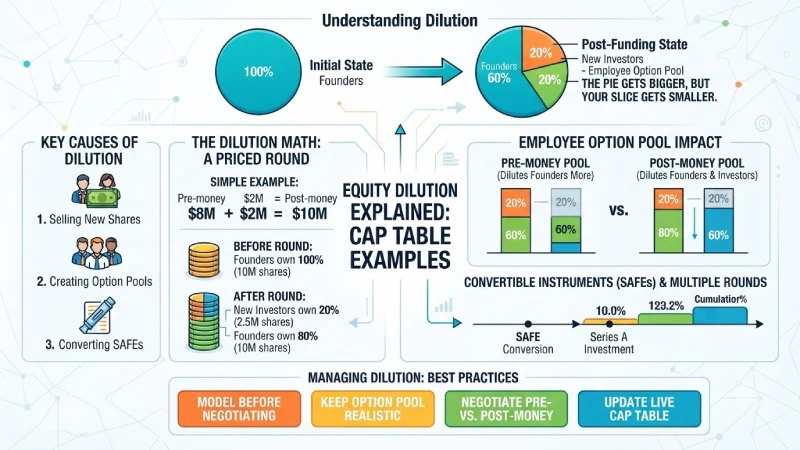
. Although the overall pie expands, each existing slice becomes a smaller part of the pie. Being familiar with the mathematics of equity dilution enables the founders to stay in better control and raise money wisely.
This article addresses the following questions: Why does equity dilution take place? What is pre-money and post-money ownership? How does the equity of employees get diluted? How do various types of convertible securities, such as SAFEs, affect the cap table? And how can you plan for several fundraising rounds at once? All of these examples are practical and based on real-life situations.
What causes founder equity dilution?
Dilution happens whenever the company creates and issues new shares (or instruments that will later convert into shares). The main causes are:
- Selling new shares to investors in a priced round
- Creating or expanding an employee option pool
- Converting SAFEs or convertible notes into equity
- Issuing shares or options to advisors, employees, or partners
- Certain anti-dilution adjustments in down rounds (less common for founders)
Equity dilution is a crucial but not well understood subject in raising money for startups. Every time a company issues stock, its existing shareholders’ equity gets diluted. Although the pie becomes bigger, each piece of the pie will now be a smaller portion of the whole pie. Understanding the principles of equity dilution allows founders to maintain control over their company and make better fundraising decisions.
The below tutorial will explain the reasons for equity dilution, how to compute pre and post-money equity, how employee stock options reduce ownership, how various convertible securities such as SAFE impact capitalization table and how to plan several fundraising rounds in advance. All the examples are real-life cases that you can use for your business.
How do you calculate ownership before and after funding?
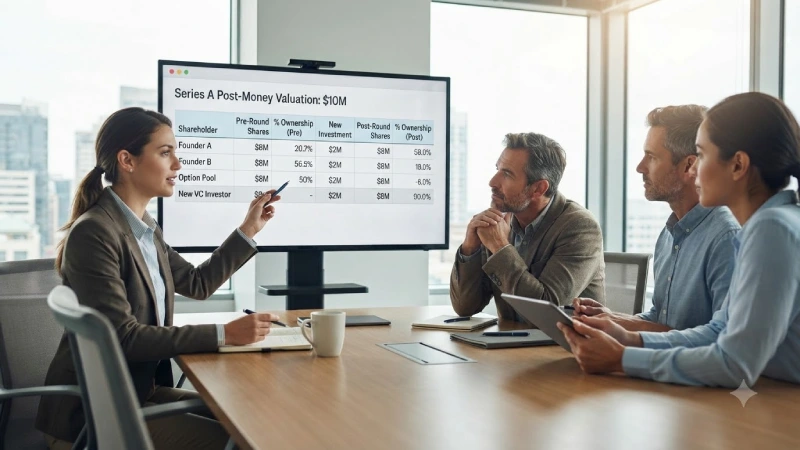
Ownership is always talked about in terms of total dilution. This means that when calculating ownership, every single share that can ever be issued is included: outstanding common stock, preferred stock, the option pool (whether granted or not), warrants, and conversion of SAFEs or notes.
Basic formula for a priced round
Post-money valuation = Pre-money valuation + Investment amount
Investor ownership % = Investment amount ÷ Post-money valuation
Existing shareholders’ new ownership % = 100% – Investor ownership %
Simple example
Both founders hold 100% equity of the company on equal basis (5 million each, totaling to 10 million shares).
They have raised $2 million at an $8 million pre-money valuation.
They raise $2 million at an $8 million pre-money valuation.
Post-money valuation = $10 million.
New investors own 20%.
Founders together now own 80% (40% each).
If the share price is set so that $2 million buys 2.5 million new shares, the total shares become 12.5 million. Each founder’s 5 million shares are now 40% of 12.5 million.
Always work from the fully diluted share count. Spreadsheet tools or cap-table platforms make the arithmetic easy once the inputs are correct.
How do employee option pools affect dilution?
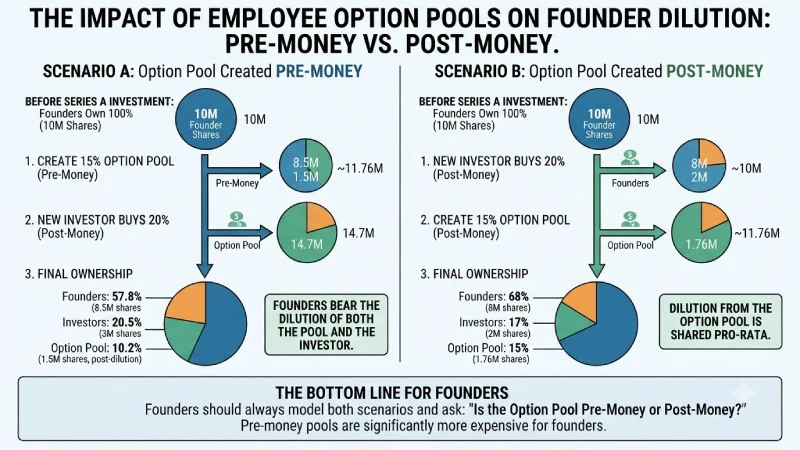
Employee stock option pools are among the largest sources of founder dilution that go undetected. It is an absolute certainty that the investors will insist upon setting aside a pool of shares for potential future hiring purposes (usually 10-20% of the fully diluted company). The key point is whether the pool is created or increased pre or post funding.
Most term sheets contain provisions that create or increase the pool pre-money. This means that the founders bear the brunt of any dilution from the employee option pool.
Example of option-pool impact
Founders own 10 million shares (100%).
Investors want a 15% option pool after the round and are investing enough to own 20% post-money.
To leave the new investors with a clean 20% and create a 15% pool, the pool and the new investment must be calculated carefully. The practical result is that founders absorb both the investor dilution and the pool dilution. Their ownership drops more than the headline 20% investor ownership suggests.
Founders should always ask: “Is the option pool calculated pre-money or post-money?” and model both scenarios. A larger pool created pre-money is more expensive for founders than the same pool created post-money.
How can convertible instruments affect the cap table?
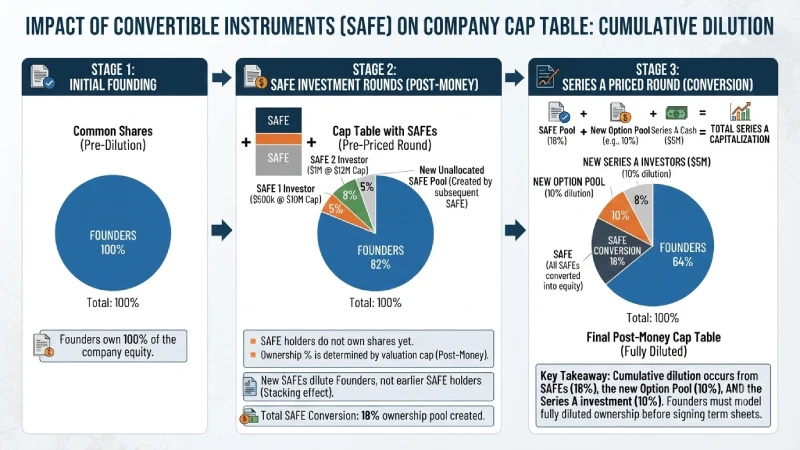
SAFEs and convertible notes do not issue shares immediately. The conversion happens later when there is an equity round or a liquidity event. The terms of the conversion will determine the number of shares that the holders will get and hence the dilution.
Post-money SAFE (most common in 2026)
Ownership percentage is fixed at the time of the SAFE.
Example: $500,000 SAFE on a $10 million post-money cap = 5% ownership when it converts, regardless of the later priced-round valuation (assuming the round is above the cap).
Multiple post-money SAFEs stack. Each new SAFE dilutes the founders and earlier common shareholders, but not the previous SAFE holders.
Pre-money SAFE
The final ownership percentage is not fixed until conversion. The math is more complex and depends on the size of the priced round and other converting instruments.
Conversion example
- The company has raised $1.5 million post-money SAFE investment with varying valuations to total up to 18% of equity.
- The company raises another $5 million of Series A at a pre-money valuation of $25 million and post-money valuation of $30 million.
- The conversion of SAFE takes place for 18% of the company.
- The investors of Series A will then get their percentage of ownership in the post-conversion and post-option pool company.
- The founders suffer the effects of cumulative dilution due to the SAFEs, the new option pool and Series A fundraising.
Always model your fully diluted ownership with conversion of all outstanding SAFEs and notes before signing the term sheet of the new priced round.
How do founders model multiple funding rounds?
It is not that an intelligent entrepreneur just thinks of one round; he develops a straightforward dilution model, which takes into account multiple rounds such as seed, series A, series B, and in some cases series C as well.
Basic multi-round example (approximate 2026 medians)
Basic multi-round illustration (approximate 2026 medians)
| Stage | Typical Dilution | Approximate Founder Ownership After Round |
| Incorporation | — | 100% |
| Pre-seed/SAFE | 10–20% | 80–90% |
| Seed | 15–20% | 65–75% |
| Series A | 18–23% | 50–60% |
| Series B | 15–20% | 40–50% |
| Series C | 10–15% | 35–45% |
They are medians and have been simplified. Actual numbers will depend on what the actual percentages sold, top-ups to option pools, and the use of pro-rata by previous investors are.
How to build your own model
- Start with the current fully diluted equity positions.
- In each future round, enter the projected raise size and the projected pre-money valuation (or projected dilution percentage).
- Include any additional option pools.
- Calculate the updated ownership percentages.
- Repeat this process for each successive round.
- Test various valuation cases (optimistic, base, and conservative).
Most founders use a spreadsheet. Cap-table software can also run these projections. The goal is to see whether you will still own a meaningful percentage after the rounds you realistically expect to need.
Practical tips for managing dilution
- Model dilution before you negotiate any term sheet.
- Keep the option pool as small as realistically needed for the next 12–18 months of hiring.
- Prefer post-money SAFEs when the terms are standard, but understand the stacking effect.
- Negotiate the option-pool treatment explicitly.
- Preserve enough ownership so that later rounds and employee grants still leave founders with real upside.
- Keep in mind that sometimes the smaller the percentage of the huge company can be worth more than the bigger percentage of the small company.
Common mistakes
- Looking only at the headline valuation and ignoring the option-pool and SAFE conversion effects.
- Creating an oversized option pool “just in case.”
- Failing to model the cumulative effect of three or four rounds.
- Accepting high dilution early because “we need the money,” without a clear plan for how the capital increases value.
- Not updating the live cap table after every SAFE, note, or option grant.
Troubleshooting
My ownership is dropping faster than I expected.
Rebuild the model with every outstanding SAFE, note, and the current option pool. Small instruments add up.
Investors want a larger option pool than I planned.
Ask what hiring plan justifies the size. Negotiate the timing (pre- vs post-money) and the exact percentage.
I have several SAFEs with different caps.
List them all, calculate each conversion percentage, and sum the total SAFE ownership before modelling the priced round.
I am not sure how much dilution is “normal.”
Use current market medians as a reference, then adjust for your traction, sector, and negotiation strength. The correct amount is that which leaves you still motivated and in control but gives investors a decent amount from a growing business.
Frequently Asked Questions
Is dilution the same as losing value?
No. Dilution reduces your percentage. The value of that percentage can still increase if the company grows faster than the dilution rate.
Should I minimise dilution at all costs?
No. Raising too little capital or at the wrong time can hurt the company more than moderate dilution. Balance ownership against the progress the capital enables.
Do employee options dilute founders?
Yes, when the pool is created or expanded. Once options are granted and exercised, the dilution has already occurred at the pool-creation stage.
How often should I update my dilution model?
Update it whenever you sign a new SAFE or note, change the option pool, or begin serious discussions for a priced round.
Can anti-dilution protection help founders?
Standard anti-dilution clauses protect preferred investors in down rounds. Founders usually hold common shares and do not receive the same protection.
Conclusion
Equity dilution is an exercise in arithmetic, not in magic. Each time you issue a share, ownership percentages go down. The factors to take into account are: how much money you’ll raise, at what valuation, the option pool size and when to set it aside, and the details of the conversion of any SAFEs and notes that you might issue.
Founders who create clear models early on during negotiations end up with more ownership and make more rational decisions. They understand how expensive each round is going to be in terms of dilution, and whether the capital raised is worth the price.
Back to the main Equity Financing pillar page for an overview of all topics in this pillar. For details on angels, venture capital process, valuation, term sheets, and equity versus debt, proceed to cluster guides. Do the math, stay organized, and use dilution to your advantage.