Where do I start? First of all, refer to the main pillar guide on Equity Financing and then to this particular guide to learn about how to approach angel investors in preparation and collaboration.
Angel investors are often the first professional money that comes to a startup. They make personal cheques worth around $25,000 – $250,000, even more at the pre-seed or seed stages. In 2026, they will still be among the key sources of early funding, particularly for those founders who are not quite prepared for institutional venture capital.
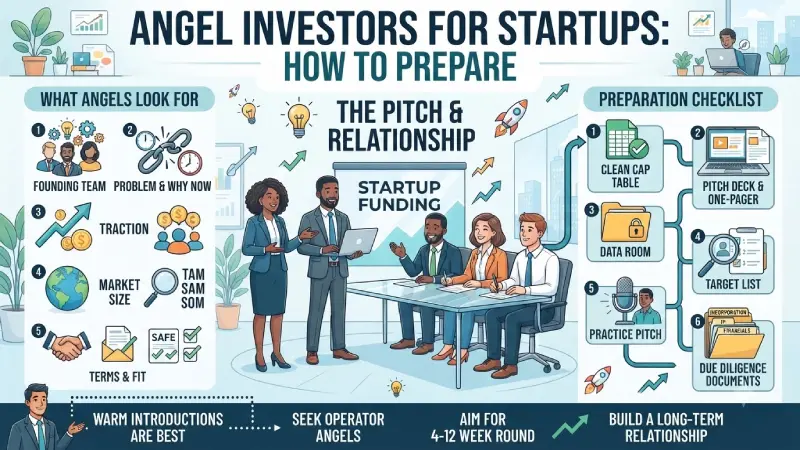
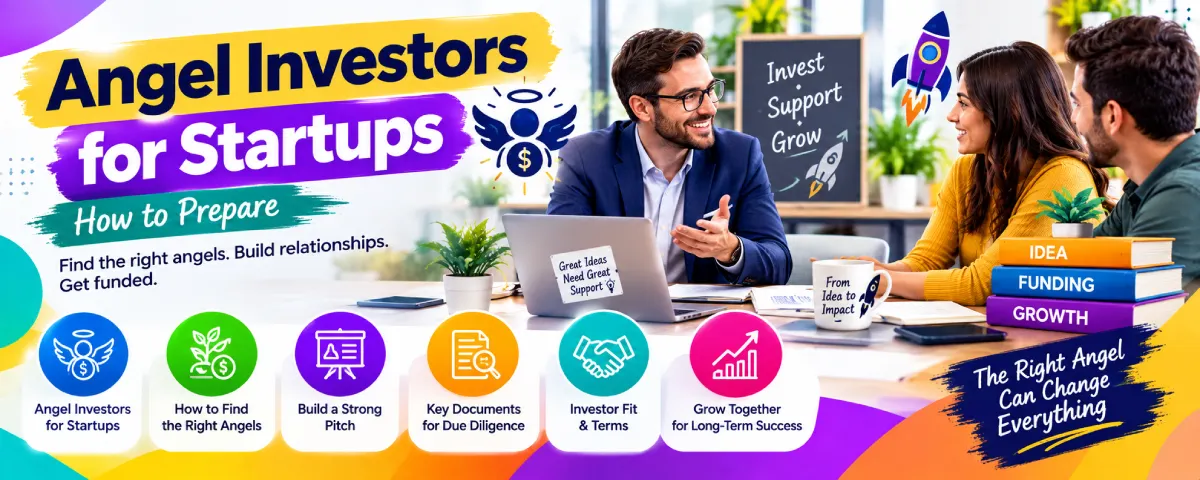
This guide explains what angels really look for, how to find the appropriate ones, what elements to include into an effective pitch, what documents will help them in their due diligence process, and how to analyze the compatibility of the investors and terms of investment.
What do angel investors look for in startups?
Angel investors use their own money. It affects how they see investment opportunities in comparison to venture funds. In 2026, most angel investors pay attention to five main sectors.
- The founding team
It is always the most weighted criterion. Angels want to see expertise, persistence, integrity and complementarity of skills. Having an engineer working with salesperson is always a good idea. Being a serial entrepreneur leads to success more often than not, however, the first time founder with excellent customer insight still closes cheques. Angels watch your ability to discuss the problem, learn from the mistakes and communicate the idea clearly. - The problem and why now
The problem needs to be specific and serious enough for customers to pay for its solution. Abstract statements like “small companies require better technology” don’t work. Effective pitches demonstrate clear evidence of the existence of this pain and new opportunities due to the change in timing or technology. - Early traction or proof of demand
In 2026, idea-stage deals become more difficult. Angels need to see some traction, pilots, solid waitlist conversion numbers or even just patterns in repeatable customer interactions that indicate a true willingness to pay, even if it’s a small number. - Market size and path to scale
Angel investors still need big returns. They like to see markets where an exit is possible. On the other hand, angels still want to see a feasible way to create a beachhead market. - Terms and structure
A SAFE deal with a very high valuation will discourage sophisticated angels. Standard SAFEs with sensible caps are fine. Cap tables that make sense, along with founder vesting, all work well too.
Chemistry is another important factor. The angels are betting on the people they will be dealing with for many years to come. Being arrogant, being defensive or being uncurious can easily ruin a good deal regardless of the numbers being very good.
Where can founders find relevant angel investors?
Angels require a more refined approach than cold emails do. The most efficient routes to conversion in 2026 include:
Warm introductions
The most effective way to succeed. Contact those entrepreneurs that have pitched themselves to angels, mentors, accelerators, and/or lawyers. Be brief and specific with your pitch.
Angel groups and syndicates
Many cities and regions have organised angel networks. These groups often review deals collectively and can assemble larger total cheques from multiple members. Syndicates on platforms also allow one lead to bring in others.
Operator angels
Past or present executives and founders of scaling organizations within your industry. They know what you face and who can be helpful to your cause. They’re still reachable via LinkedIn and industry events.
Investor databases and platforms
Tools that list angels by sector, stage, cheque size, and geography help build a target list. Filter hard so you only approach people who actually invest in companies like yours.
Accelerators and demo days
Demo days and contacts from alumni can do the trick even if you’re not in any program.
Online communities and social platforms
A few angels will be active on X (Twitter) or LinkedIn and will like good content. It’s not very quick, but this will bring you inbound leads.
Get a list of 100-200 names and prioritize them. Begin with those which match you strongly or possibly well and polish your pitch before approaching the “dream” names. You need to record every conversation so that you can determine who has seen your deck, who wants to know more about it, and who turned you down.
What should an investor pitch include?
A good angel pitch is short, clear, and honest. Most angels decide whether to continue after the first meeting or deck review.
Core elements of a strong pitch deck (10–15 slides)
- Problem – specific and painful
- Solution – what you do and why it is different
- Why now – timing or technology shift
- Market – total size and your beachhead
- Product or demo – show, do not just tell
- Traction – real numbers, even if early
- Business model – how you make money
- Go-to-market – how you will acquire customers
- Team – why you are the right people
- Competition – honest view of alternatives
- Financials – simple projections and use of funds
- The ask – how much you are raising and on what terms
Keep slides visual and sparse. Time the pitch at 10-12 minutes so there is time for Q&A.
Many angels will also want to see a one-pager that they can forward along. Put together a small data room with the documents mentioned below.
Be ready for direct questions:
- What have you learned from customers so far?
- What is the biggest risk right now?
- How will you use the money and what milestones will it achieve?
- What does the cap table look like today?
Honest, specific answers build more trust than polished spin.
Which documents support angel due diligence?
Angel due diligence is lighter than venture capital diligence but still real. Organised founders close faster and look more professional.
Documents most angels request or expect
- Current and historical capitalisation table
- Certificate of incorporation and governing documents
- Founder equity and vesting agreements
- Intellectual property assignment agreements
- Cap table showing all outstanding SAFEs, notes, or options
- Basic financials (bank balances, monthly burn, runway)
- Customer contracts or pilot agreements if any exist
- Pitch deck and one-pager
- Team bios and relevant background
For firms that already have income, angel investors typically ask for documentation from the payment processors or just revenue statements. For firms that do not yet have any revenue, documentation on conversations with potential customers can be helpful.
These documents should be readily available in the shared folder prior to commencing discussions. If not properly organized, the lack of documentation will cast doubts on your idea despite its merits.
Reference checks are part of due diligence. The angels may get in touch with your past colleagues, early clients, and other investors.
How do founders evaluate investor fit and terms?
But not every cheque is worth taking. Founders have to diligence the angel just as the angel does the startup.
Questions to ask yourself and the investor
- Does this person understand my sector or customer?
- Have they invested at my stage before?
- What is their typical cheque size and follow-on behaviour?
- How do other founders describe working with them?
- Do they desire a seat on the board, and is it constructive for them to do so?
- Are the proposed terms standard or unusually aggressive?
Common term considerations with angels
- Valuation or SAFE cap – is it reasonable for the stage and traction?
- Instrument – post-money SAFE is widely used and relatively founder-friendly when terms are standard
- Information rights – light reporting is normal; heavy control rights may not be
- Pro-rata rights – useful if the angel can follow on later
- Board or observer rights – early board seats from small cheques can create governance complexity
Talk to other entrepreneurs who have been funded by the same angel before. Talk about his/her responsiveness, helpfulness, and behaviour during tough times.
Occasionally, it would make more sense to value a friendly angel slightly less rather than value an unfriendly angel more.
Practical preparation checklist before you start raising from angels
- Clean and update the cap table
- Prepare a clear 10–15 slide deck and one-pager
- Organise a simple data room with the core documents
- Build a target list of 100+ relevant angels and tier them
- Practise the verbal pitch until it feels natural
- Decide your raise amount, instrument, and target terms in advance
- Line up warm introduction paths
- Set a realistic timeline (most angel rounds take weeks to a few months)
Common mistakes founders make with angels
- Approaching investors who do not invest at their stage or in their sector
- Overvaluing the company relative to traction
- Sending long, unfocused decks
- Failing to follow up consistently
- Accepting money from people who create more problems than value
- Neglecting the cap table and legal hygiene
- Treating every conversation as a transaction instead of a relationship
Troubleshooting
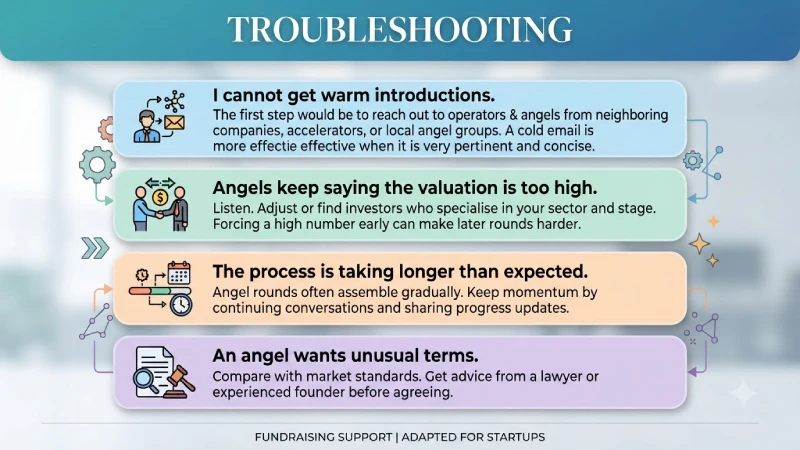
I cannot get warm introductions.
The first step would be to reach out to operators angels from neighboring companies, accelerators, or local angel groups. A cold email is more effective when it is very pertinent and concise.
Angels keep saying the valuation is too high.
Listen. Adjust or find investors who specialise in your sector and stage. Forcing a high number early can make later rounds harder.
The process is taking longer than expected.
Angel rounds often assemble gradually. Keep momentum by continuing conversations and sharing progress updates.
An angel wants unusual terms.
Compare with market standards. Get advice from a lawyer or experienced founder before agreeing.
Frequently Asked Questions
How much money do angels usually invest?
An angel’s cheque size normally ranges from $25,000 to $250,000, but higher amounts can be attained by syndicates.
Should I have a warm introduction?
It is best if you have warm introductions, but well targeted cold pitching may help too when there is an obvious fit.
SAFE vs priced round: which one to choose when fundraising from angels?
In 2026, most early angel investments will use post-money SAFEs due to their simplicity. More often, priced rounds will be used with increased funding size.
How long does it generally take to close an angel round?
Many rounds from initial talks to money in the bank can be closed within 4 to 12 weeks, although sometimes it takes more time.
Is it possible for angels to lead a round?
Yes, some seasoned angels or angel groups can be lead investors and help pull in other investors.
What happens when an angel demands a board position with a small investment?
Beware, board complications early on may bring you troubles. Observer rights or advisory status may work better.
Conclusion
In 2026, angel investors still rank as one of the most available sources of funds for startups. They act fast, write good cheques and usually bring more than just money by providing their experience and network.
Everything comes down to how well-prepared you are: knowing what they’re looking for, creating a list that fits, telling your story consistently and truthfully, and bringing the necessary documentation, as well as assessing whether you fit too.
Approach the interaction not as a single transaction but as the start of a long-lasting relationship. The best angel relationships snowball over time and across several rounds.
Go back to the main Equity Financing pillar page for the full picture and explore other cluster pages as you need details about venture capital, dilution, valuation, term sheets or equity vs. debt financing. Be well-prepared, be truthful and pick people who will still be able to help you in tough times.