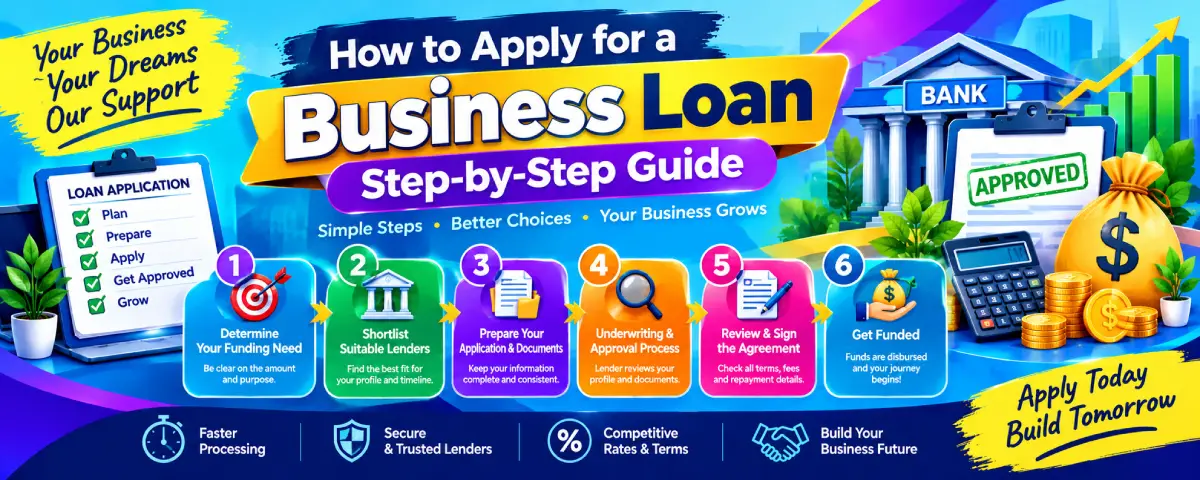
Making the process of securing a business loan easier would be made easy by following these guidelines: determine the amount of money you need find the appropriate lenders for your case fill up the loan application forms learn about underwriting and thoroughly read through the loan agreement before signing it. The Business Loans guide together with its pages containing details on types of business loans conditions interest rates would assist you in securing a business loan.
Where This Fits
You are aware of the general types of loans, the com A request that is much more than what you can defend yourself on can raise many issues relating to planning and can end up with reduced approval amounts. mon barriers to eligibility, and how interest and fees operate. It is now time to use what you have learned. The logical pages to follow from here are generally:
- Secure vs. unsecured structure choice → Secured vs Unsecured Business Loans
- Lend repayment and cash flow planning → Business Loan Repayment
How Much Funding Does Your Business Need?
Start with a precise number and a clear purpose. Lenders respond better to specific, justified requests than to vague “I need working capital” statements.
- Calculate the real need
List every cost the funds will cover. For equipment, include the purchase price, taxes, shipping, installation, and a small buffer. For inventory, use current supplier quotes plus a realistic turnover period. For expansion or hiring, project the costs for the next 6–12 months and show how the investment is expected to generate revenue that covers the new payments.
- Add a modest buffer, not a large one
Most experienced owners add 5–15% for unexpected costs. Requesting much more than is justified may bring up issues regarding planning, which could result in a smaller amount being approved or a higher rate.
- Test affordability before you apply
Estimate the monthly payment for the amount and term you have in mind. Take out that figure from your expected monthly net cash flow. Allow for some buffer room (20-30% usually is a realistic expectation). If the amount is going to eat up most of your available cash, lower your demand for the loan or extend the time period.
- Match amount to product
A $40,000 equipment purchase often fits equipment financing cleanly. A $300,000 expansion may point toward an SBA 7(a) or bank term loan. A fluctuating $15,000–$25,000 monthly need is usually better served by a line of credit than a fixed term loan.
A clear, costed purpose strengthens every later stage of the application.
How Do You Shortlist Suitable Lenders?
Just because a lender exists does not mean that you will make a good match with them. Do some filtering first to save you from making needless inquiries.
Match lender type to your profile and timeline
- Strong credit, 2+ years in business, solid revenue, can wait 30–90 days → Traditional banks and SBA preferred lenders.
- Decent credit, 6–12 months in business, need funds in days or a couple of weeks → Online and fintech lenders.
- Buying specific equipment → Equipment financing specialists.
- B2B invoices outstanding → Invoice financing or factoring companies.
- Very fast capital and higher tolerance for cost → Short-term online or revenue-based products.
Use prequalification tools when available
A number of online lending companies and also some marketplaces provide prequalification using a soft credit check. This is how you can know the amount that you can borrow and at what interest rates. It will guide you to reduce your choices.
Check current lending appetite
Lenders change focus Some focus on particular sectors or loan amounts at various times. A brief talk or chat session will tell you if your profile falls within their scope at the time.
Consider relationship value
If you already bank with a strong small-business lender, start there. Existing relationships sometimes produce better terms or faster decisions. Still compare at least one or two outside options so you know the market rate.
Practical short-list criteria
- Minimum credit score and time-in-business requirements you meet
- Typical funding speed that fits your timeline
- Reputation for clear communication and reasonable documentation requests
- Transparent fee structure
Aim for three solid candidates rather than ten scattered applications.
How Do You Prepare the Application and Documents?
” The Preparation stage helps to improve both speed and chances of obtaining approval. When the whole set of files is complete and consistent, the procedure is faster and more professional.
Core document checklist (2026 norms)
| Document | Banks / SBA | Online Lenders | Equipment Financing |
| Business tax returns (1–3 years) | Required | Often 1–2 years | Frequently |
| Personal tax returns (guarantors) | Required | Often required | Often required |
| Business bank statements (3–12 mo) | Usually 12 months | Usually 3–6 months | 3–6 months |
| Year-to-date P&L and balance sheet | Required | Frequently | Helpful |
| Debt schedule | Required | Strongly preferred | Helpful |
| Use-of-funds / business plan summary | Required (esp. SBA) | Sometimes | Quote or invoice |
| Formation docs, EIN, ownership | Required | Required | Required |
| Personal financial statement | Often required | Sometimes | Sometimes |
Organize digitally
Create clearly labeled PDF folders. Name files so an underwriter can find them instantly (e.g., “2025 Business Tax Return – ABC LLC.pdf”). Inconsistent or missing pages are one of the most common sources of delay.
Ensure numbers tell the same story
Revenue on the tax return should align reasonably with bank deposits. The debt schedule should match what appears on the credit reports and financial statements. Large unexplained transfers or cash activity should have a short written explanation ready.
Write a clear use-of-funds paragraph
Two to four sentences that state the exact purpose, the amount, and how the investment is expected to support repayment. Specificity helps.
Timing
Start gathering documents 3–6 weeks before you plan to submit. Tax-season delays, accounting lags, or missing bank statements can stretch the process.
What Happens During Underwriting and Approval?
Once you submit, the file enters underwriting—the lender’s detailed risk review. Understanding the stages reduces anxiety and helps you respond quickly to requests.
Typical stages
- Initial verification — Confirms basic identity, business existence, ownership, and that required documents are present. Often partially automated.
- Credit and data review — Individual and corporate credit checks are performed. Financial statements and records are reviewed for cash flow trends, outstanding debts, and accuracy.
- Underwriting analysis — For a human underwriter, who will review large or complicated cases, debt coverage, industrial risk, asset value, if any, and ability to repay will be considered.
- Decision — Approval, conditional approval (with items still needed), counter-offer (different amount or terms), or denial.
- Closing preparation — If approved, final documents, guarantees, and any collateral paperwork are prepared.
Timelines in 2026
- Internet term loans and lines of credit: usually 24 hours to 7 – 10 days.
- Term loans from banks: 2 to 6 weeks is typical.
- SBA loans: typically 30 – 90 days, longer in some cases for complicated applications.
- Financing equipment purchases: generally 3 – 14 days after receipt of quote from vendor and basic documentation.
What underwriters focus on
Cash flow stability and ability to service the additional payment with some margin (DSCR), creditworthiness, document consistency, and, where applicable, the value and quality of the collateral. A clear file with consistent numbers processes faster than an inconsistent but more solid one.
How to help the process
Respond to document or clarification requests within 24–48 hours. Keep your phone and email available. If something in the financials looks unusual (a one-time large expense or revenue spike), provide a short written explanation proactively.
What Should You Check Before Signing the Loan?
Approval is just the start. The final agreement is the one that contains the terms you must follow.
Key items to review carefully
Amount of loan and whether any fees have been deducted from the total loan amount
- Interest rate (fixed or variable) and the conditions when the variable interest rate may be subject to change
- APR along with all other fees (origination fee, closing fee, prepayment fee, etc.)
- Repayment schedule, frequency of payments, and the start date of payments
- Conditions of prepayment – can you repay the loan earlier?
- Description of the collateral along with the conditions when the lender is allowed to take control of your assets
- Language concerning the personal guaranty and whose signature is required
- Default conditions and what qualifies as a default
- Post-funding reporting or financial covenants
- Legal jurisdiction and dispute resolution provisions
Compare the final documents to the earlier offer
Numbers sometimes shift slightly between verbal or email offers and the final paperwork. Confirm everything matches what you expected.
Ask questions
In case there are some clauses that are not clear to you, seek clarifications before signing the document. This is quite reasonable.
Final affordability check
Look at the actual payment amount and schedule against your current cash-flow forecast one more time. If the payment feels tight, discuss options (slightly longer term, lower amount, or different product) before signing.
Once you sign and the funds are disbursed, the repayment phase begins. Set up automatic payments if possible and track the loan the same way you track any major business expense.
Practical Comparison Tables
Typical application-to-funding timelines (2026)
| Lender / Product Type | Typical Time from Complete Application to Funding |
| Online term loan / line | 1–10 days |
| Equipment financing | 3–14 days |
| Traditional bank term loan | 2–6 weeks |
| SBA 7(a) or 504 | 30–90 days (sometimes longer) |
| Invoice financing | 1–5 days once invoices are verified |
Document readiness impact
| File Quality | Likely Effect on Process |
| Complete, consistent, labeled | Faster review, fewer questions |
| Missing pages or mismatched numbers | Delays, additional requests, higher chance of decline |
| Vague use of funds | Extra scrutiny or lower approval amount |
| Proactive explanations for anomalies | Smoother underwriting |
Frequently Asked Questions
What is the typical timeline for the whole process?
From document gathering to loan funding: several days to a couple of weeks for many online products; 1 to 3 months for many banking and SBA loans.
Does an application affect my credit score?
Hard inquiries could affect your credit score temporarily. Soft inquiry prequalification tools help you explore different options without damaging your credit score. Avoid applying for too many loans.
If there is a denial, what is next?
Check the exact reason behind it. The possible ways out might be to improve your credit rating, reduce the amount you need, pledge security or just wait for some more time since you started your business. Try again.
Can I apply to several lenders simultaneously?
Yes, but just do it to a few matching lenders. Otherwise, you may face many hard credit inquiries.
Do I have to provide my business plan for all loans?
You may not need a complete business plan for all loans, especially if you apply for an SBA loan. It may suffice to submit a concise summary of how you plan to use the money.
Troubleshooting Common Application Problems
Documents keep getting requested
Your original package was likely incomplete or inconsistent. Pause, organize everything cleanly, and resubmit a full set rather than sending pieces one at a time.
Underwriting is taking longer than expected
Follow up politely once a week. Ask whether any items are still outstanding. Complex files, high volume at the lender, or SBA secondary review can extend timelines.
The approved amount is lower than requested
This is common. Evaluate whether the lower amount still solves the core need. You can sometimes accept the partial approval and seek a second facility for the remainder if cash flow allows.
Terms changed between offer and final documents
Do not sign until the discrepancy is resolved. Ask for a corrected agreement or a written explanation.
Conclusion
Borrowing money through a business loan can be an easy task when done properly with adequate planning and proper sequence. The borrower must choose the exact amount he needs along with the purpose. He should select the lenders that meet his criteria and requirements, gather all documents required by a lender, know what a lender expects from the applicant and read each and every term carefully before signing the agreement. This can make the process from decision to funding a smooth one and the borrower may get financed without being troubled by the process. For further information about secured and unsecured loans, visit our relevant cluster pages.