The process of securing a loan for your business begins with a single fundamental question: Are you eligible?
Not all loan applications get approved. Lenders take into account a number of criteria that determine if you can afford the loan and will repay it. Being aware of eligibility criteria will help you be more prepared, avoid unnecessary refusals, and select the right kind of loan.
In this article, we will explore what business loan eligibility is, the key criteria that lenders consider, requirements per different types of loans, needed documentation, and other practical recommendations to increase your chances.
What Business Loan Eligibility Means
“Eligibility for business loans is the criteria that are used by the financier to determine whether your company is a good candidate to receive financing. Put simply, it is the way of measuring risk prior to approving or rejecting your loan application.”
The financiers are not interested only in your need for money. They are concerned with the following issues:
- Can your business realistically repay the loan on time?
- How stable and established is the business right now?
- What is the overall risk if they decide to lend you the money?
Should the answers to such questions seem favorable, the likelihood of approval will be much higher. Should the answers give cause for concern, the lender might deny the application, provide less funding, or apply a higher interest rate.
However, being eligible does not apply equally to all forms of loans. It varies depending on:
- Traditionally, loans from banks have been the most stringent in their criteria.
- Online loans and other forms of financing can be more flexible.
- The loan for equipment financing is likely to be more based on the worth of the equipment rather than the history of the business.
- The government-guaranteed loans (like SBA loans in the US) have their own set of criteria.
- Loans for startups and microloans also have specific criteria.
Due to these factors, a business entity that cannot get a term loan from the bank could be eligible for online working capital loans, equipment financing, or even revenue-based loans.
Understanding eligibility helps you in three practical ways:
- You can prepare the right documents and information in advance.
- You can choose lenders whose requirements match your current situation.
- You can improve weak areas (such as credit score or documentation) before you apply.
In other words, a business loan application is more than just a list. This is how lenders evaluate if your business poses an acceptable level of risk for them. A more pronounced profile increases your chances of success greatly.
Key Factors That Affect Business Loan Eligibility
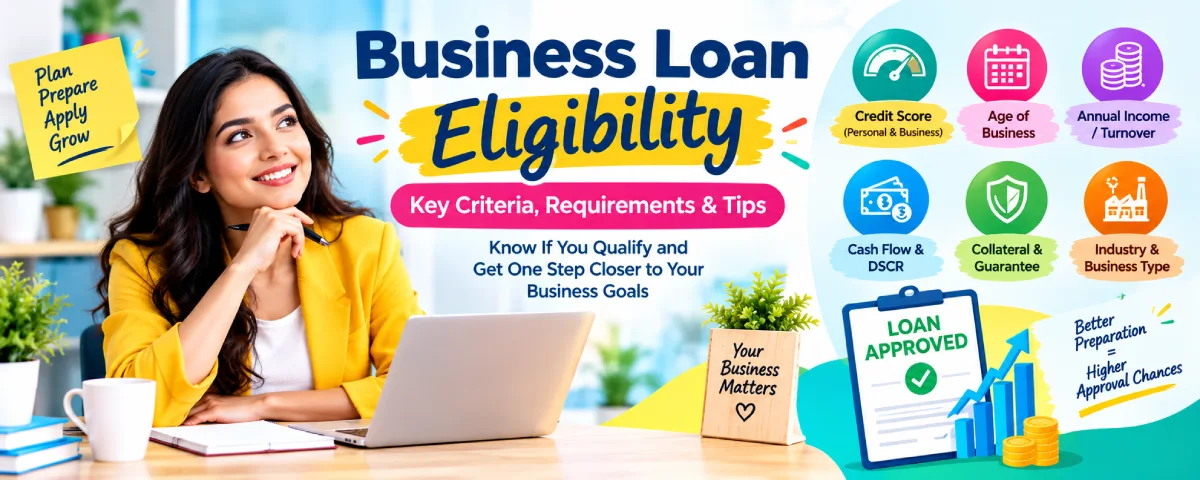
Most lenders look at a combination of these factors:
Credit Score (Personal and Business)
Your own personal credit score is very significant, even more so for small businesses. Most lenders would rather have a score of 670 or more for an individual’s credit. Higher scores (700 to 720+) offer better chances and terms. Business credit scores are also taken into account after a certain time in the market.
Age of Business
The time since you started your business plays an important role here. Most traditional financial institutions will require a minimum of 2 years of business operation. Some other alternatives will be fine if you have 6-12 months of experience in business.
Annual Income / Turnover
The lenders will need to see how much money does your business earn annually. Minimum amounts start from $100,000 annually for most online lenders, although traditional lenders want more income.
Cash Flow and Debt Service Coverage
The lenders would be interested in finding out how much cash is generated in order to pay off old debts as well as the new loan. This is usually evaluated using the Debt Service Coverage Ratio (DSCR). DSCR greater than 1.15–1.25 is normally preferred.
Collateral and Personal Guarantee
Some loans may need collateral (the assets that the lenders can take if there is a default on payment), while others may need a personal guarantee from the borrower.
Industry and Business Type
But then there are some businesses which are considered to be risky businesses.
Documentation and Compliance
Maintaining clean bookkeeping and tax record keeping will make one more eligible.
Key Business Loan Eligibility Criteria Summary
| Factor | What Lenders Look For | Typical Strong Profile | Typical Weak Profile | How to Improve |
| Personal Credit Score | Ability to repay and financial responsibility | 700+ (ideally 720+) | Below 650–670 | Pay bills on time, reduce credit utilization, fix errors |
| Time in Business | Stability and track record | 2+ years | Less than 6–12 months | Build operating history, consider alternative lenders |
| Annual Revenue | Capacity to support loan payments | $100,000–$250,000+ (depending on loan type) | Very low or highly inconsistent revenue | Focus on steady sales and clean bank deposits |
| Cash Flow / DSCR | Ability to cover existing + new debt | DSCR above 1.25 | DSCR below 1.15 or negative cash flow | Improve collections, control expenses |
| Documentation | Clarity and professionalism | Complete, organized, up-to-date records | Missing, outdated, or messy documents | Create finances and taxes before hand |
| Existing Debt | Overall risk level | Manageable debt levels | High-interest or heavy existing debt | Reduce high cost debts before applying |
| Industry | Risk category of the business | Lower-risk or preferred industries | High-risk or restricted industries | Stress stability aspects or select the right lender |
| Use of Funds | Clear and productive purpose | Specific, growth-oriented plan | Vague or high-risk use of funds | Explain in detail the purpose of the loan |
Typical Eligibility Requirements by Loan Type
| Loan Type | Typical Credit Score | Time in Business | Minimum Revenue | Other Common Requirements |
| Traditional Bank Term Loan | 680–720+ | 2+ years | $250,000+ per year | Strong cash flow, collateral often needed |
| SBA 7(a) Loan | 660–680+ | 2+ years | Varies (cash flow focus) | U.S.-based, for-profit, size standards |
| Online Term Loan | 550–650+ | 6–12 months | $100,000+ per year | Steady bank deposits |
| Business Line of Credit | 660–700+ | 1–2 years | $100,000–$250,000+ | Good cash flow |
| Equipment Financing | 550–630+ | 6+ months | $10,000+ per month | Equipment serves as collateral |
| Working Capital Loan | 600–680+ | 6–12 months | $15,000–$25,000/month | Consistent revenue |
| Merchant Cash Advance | 500+ | 3–6 months | $10,000+ per month | Strong card sales or deposits |
These are typical ranges. Exact requirements vary by lender and country.
Documents Usually Required
Documents required by lenders include:
- ID/proof of ID/address
- Registration of business
- Bank statement (generally, past 3 to 12 months)
- Tax returns (individual and company, past 1 to 3 years)
- Profit & Loss account and balance sheet
- GST/Sales Tax Return
- Business plan or purpose of fund usage
- Proof of ownership
- Collateral documentation, if needed
Having these documents on hand before taking out the loan will be helpful.
How to Improve Your Business Loan Eligibility
Eligibility is not permanent. There are certain measures that companies can adopt to increase their chances of eligibility for loans even before making an application. Here are some of them.
- Check and improve your personal credit score before applying
Personal credit score is one of the very first things that the lender will check. Obtain your credit report and address all mistakes in it and concentrate on making timely payments. Even a slight increase in credit score can lead to much better offers. - Keep clean and up-to-date financial records
Lenders like organized and understandable financials. Keep your profit and loss statements, balance sheets, and tax records organized and up-to-date. Inaccurate and disorganized financials may delay or even stop the loan process. - Build business credit if possible
After registration, establish a credit record for the business. Pay bills for the business timely and have dealings with the business vendors that report to business credit agencies. A better business credit record will limit your dependence on your personal credit in the long run. - Show consistent revenue and positive cash flow
The banks and lenders favor business entities that earn a good amount of income. Make sure you have steady monthly income and cash flow. Statements from your bank account showing consistent deposits are really valuable. - Reduce existing high-interest debt if feasible
Your high amounts of current debts will negatively affect your qualification. You should try to repay those debts as much as you can before applying. It will improve your debt coverage ratio. - Prepare a clear explanation of how you will use the loan
The financial institutions want to know what you want to use the borrowed money for. Make sure you explain everything about your plan and how it will benefit your business. - Consider starting with smaller or alternative financing to build history
If you cannot yet qualify for a larger bank loan, start with a smaller online loan, equipment financing, or a business credit card. Successfully repaying smaller financing helps build a positive track record. - Apply to lenders whose requirements match your current situation
Every financier is not created equal. Study lenders which lend money to companies at a similar stage as your company. This will save you time and effort.
Practical Tip
Tips for Implementation
Improve what you have control over first, namely, your credit score, documentation, and purpose of the loan. This is where you will see the most improvement.
Common Reasons Applications Get Rejected
- Low credit score
- Too little time in business
- Insufficient or inconsistent revenue
- Poor cash flow
- Incomplete or messy documentation
- High existing debt levels
- Industry restrictions
Understanding these reasons helps you fix issues before you apply.
Practical Tips by Business Stage
| Business Stage | Realistic Options | Focus Area |
| Startup (0–12 months) | Equipment financing, microloans, online lenders, revenue-based options | Build revenue history and credit |
| Early growth (1–2 years) | Online term loans, lines of credit, some SBA options | Strengthen cash flow and documentation |
| Established (2+ years) | Bank loans, SBA loans, larger term loans | Optimize for better rates and terms |
Final Thoughts
Eligibility for a business loan largely consists of proving to the lender that your business is able to pay back the money borrowed. These include your credit score, years of experience, income, and cash flow.
The silver lining is that there is no strict eligibility criteria for a loan. Many business owners have been able to increase their chances through improving their credit score, having proper financial documentation, and approaching lenders according to their own level.
All you need to do is evaluate your credit score, your financial paperwork, and the status of your business. After that, try matching yourself to the right kind of business loan.
If you are getting ready to get a business loan, the best way is to concentrate on those things that you can change.