Negative cash flow just refers to a situation where there is more outflow than inflow of cash in the organization within a certain period of time. That doesn’t mean that there will be any problem at all for the company. A lot of businesses encounter negative cash flow situations due to seasonality, investments made by the company itself, or the scheduling of payments. Problems happen once there is an unexpected or consistent occurrence of negative cash flow.
It is up to the organization to determine what is happening and to act accordingly.
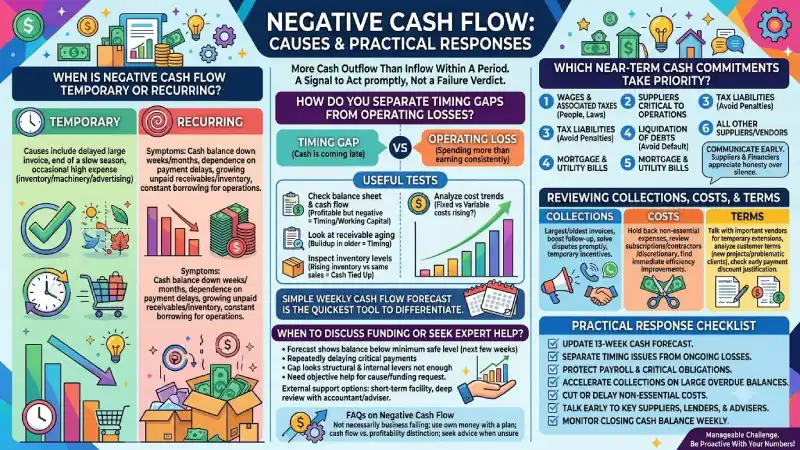
When is negative cash flow temporary or recurring?
Negative cash flow that is temporary and generally manageable is a fairly common experience. Some causes include:
- A big invoice from a client being paid only after some delay
- After a slower season, followed by a busy season
- An occasional expense on inventory, machinery, or advertising
Negative cash flow that recurs is something different. This is seen when, after correcting for seasonality and one-time expenses, there is a regular occurrence of months where cash outflows exceed cash inflows. The symptoms to look out for are: • Cash balance going down for several weeks or months
- Moving towards dependence on payment delays from suppliers or by the owners
- Increasing amount of unpaid receivables or unproductive inventory
- Requirement for constant borrowing just to fund routine operations
The significance lies in the fact that the approach to solving each problem type differs. The first one may be resolved, while the second one will require certain modifications.
How do you separate timing gaps from operating losses?
Timing mismatch occurs because the cash will come, but it is just late or irregular. Operating losses occur when the firm is spending more than earning consistently.
Useful tests:
- Check the balance sheet together with the cash flows. In case the firm is profitable, yet cash flow is negative, it might be either due to timing or working capital management.
- Look at the receivable aging schedule. If there is buildup in the older categories, the issue is one of timing.
- Inspect the inventories. In case the inventory levels are increasing while the sales remain unchanged or falling, cash is being tied up.
- Analyze the cost trends. Are fixed costs too high given the current level of revenues? Have variable costs risen?
Simple weekly cash flow forecast is likely to be the quickest tool that allows differentiating between the two issues. In case the forecast indicates that the gap will close with the arrival of known receipts, the problem is of timing. Otherwise, it is something else.
Which near-term cash commitments take priority?
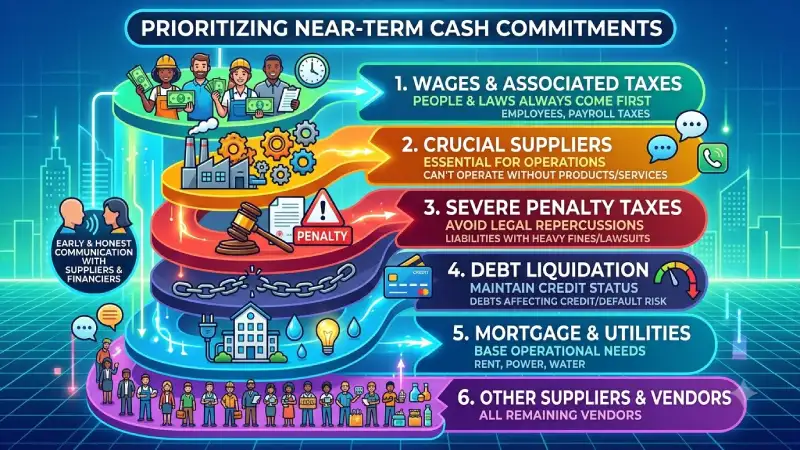
In the case of tight cash flow, prioritization becomes vital. Not all payments have equal priority or impact.
A sensible priority that companies often follow:
- Wages and associated taxes – the people and the laws always come first.
- The suppliers who make your operations impossible without their products/services.
- Your tax liabilities for which you face severe penalties and/or legal repercussions.
- Liquidation of debts that would lead to default or damage your credit status.
- Mortgage and utility bills.
- All other suppliers/vendors.
Even within this list, there should be early communication. Most suppliers and financiers will appreciate an honest discussion over continued nagging. This is also part of maintaining relationships that will be crucial after the gap.
How can collections, costs, and terms be reviewed?
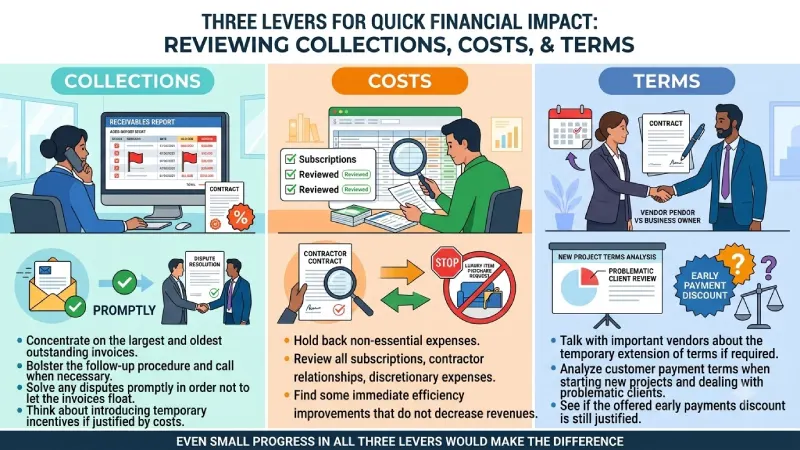
There are three main levers that provide the quickest impact.
Collections
- Concentrate on the largest and oldest outstanding invoices.
- Bolster the follow-up procedure and call when necessary.
- Solve any disputes promptly in order not to let the invoices float.
- Think about introducing temporary incentives if justified by costs.
Costs
- Hold back non-essential expenses.
- Review all subscriptions, contractor relationships, discretionary expenses.
- Find some immediate efficiency improvements that do not decrease revenues.
Terms
- Talk with important vendors about the temporary extension of the term if required.
- Analyze customer payment terms when starting new projects and dealing with problematic clients.
- See if the offered early payments discount is still justified.
Even small progress in all three levers would make the difference.
When should you discuss funding or seek expert help?
Consider external support earlier rather than later. Useful triggers include:
- The cash forecast shows the balance falling below your minimum safe level within the next few weeks.
- You are repeatedly delaying critical payments.
- The gap looks structural and internal levers are not enough.
- You need objective help to diagnose the cause or to prepare a funding request.
The options can be anything ranging from short-term facilities (such as overdraft, factoring invoices, and loans) to a more thorough analysis with an accountant or adviser. Banks and other institutions will always be more willing to help if they see that there is a clear understanding of the issue, what steps have been taken, and how the matter will be handled in the future.
Practical response checklist
- Update the 13-week cash forecast immediately with the latest information.
- Separate timing issues from ongoing losses.
- Protect payroll and critical obligations.
- Accelerate collections on the largest overdue balances.
- Eliminate any unnecessary spending.
- Start communicating with your most important suppliers early on and possibly with financiers and advisers too.
- Check the final closing cash balance every week until you reach equilibrium.
Negative cash flow is a signal, not a verdict. Treated early and systematically, most temporary gaps can be managed and many structural ones can be improved.
FAQs on Negative Cash Flow
- Does negative cash flow necessarily mean that the business is failing?
Not necessarily. There are many successful businesses which operate on negative cash flow for certain periods of time due to various reasons, including timing, seasonality, investments. The question is if the negative cash flow is normal, temporary, and manageable.
- What should I do once I see the cash balance declining?
Act as soon as possible after the forecast shows the problem to come in the next few weeks. Early intervention is usually more cost effective and stress-free.
- Should I use my own money to solve a cash flow problem?
Occasionally this may be unavoidable in the immediate future but you need to have a plan on how to reverse the situation.
- Can you tell the difference between a cash flow problem and a profitability problem?
Cash flow problems can arise even in profitable situations (timing and working capital issues). Profitability problems refer to businesses that are not making money. These two types of problems tend to go hand in hand, but the solutions are different.
- When should you seek professional advice?
When the distance is greater than your comfort level, when the reason for the problem is not clear, or if you need to talk to the lenders. A seasoned accountant will assist in clarifying the figures.
Conclusion
A situation of negative cash flow is where you have more money left over than you have taken in for that particular period of time. The key thing is to assess as quickly as possible whether the shortfall is temporary or basic, make sure you make your priorities of payment clear, and take action in respect of your collections, expenditure, and terms. Use your cash flow forecast as a means to be ahead of the numbers, be proactive with your vendors and advisers, and treat the problem as a manageable problem.