A 13-week cash flow projection is one of the most valuable forecasts for any business to perform. It does not provide strategic planning on a long-term basis. Instead, it is a short yet practical look at the funds that are about to come or go out of your account in the next three months, week-by-week. 13 weeks is a good compromise – it gives you enough time to identify potential issues, yet keeps all of the numbers feasible.
Most of the companies that end up with cash flow problems do not face difficulties for an entire year but only a few critical weeks.
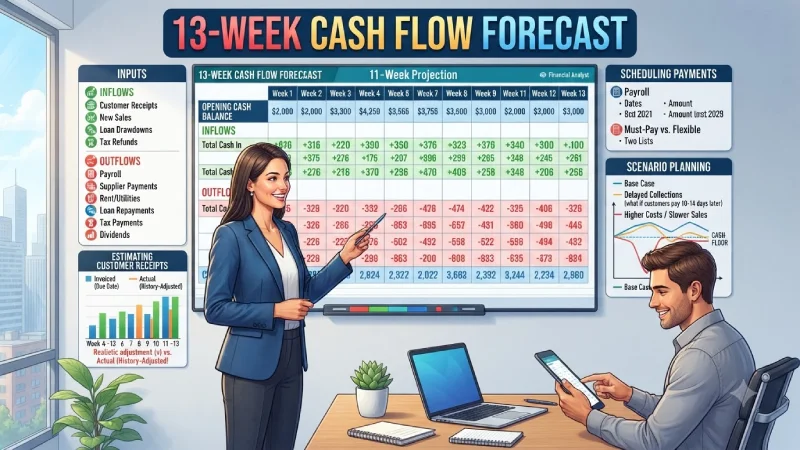
What inputs belong in a cash flow forecast?
Don’t complicate things, and keep it practical by considering actual cash flows. The framework always remains the same as follows:
- Opening cash balance (cash that is there in the bank at the beginning of the week)
- Cash inflows (expected cash flow)
- Cash outflows (expected cash flow)
- Closing cash balance (opening + inflows – outflows)
The major inputs will always be as follows:
Inflows
- Customer receipts from outstanding invoices
- New sales that will be paid within the period
- Loan drawdowns or equity injections
- Tax refunds or other one-off receipts
Outflows
- Payroll and related taxes
- Supplier and vendor payments
- Rent, utilities, and regular bills
- Loan repayments and interest
- Tax payments
- Owner draws or dividends
- Any known one-off costs
Use the direct method — actual cash in and cash out. Do not start from profit and try to adjust. That approach hides the timing problems you are trying to see.
A useful rule many teams follow: if it does not move the bank balance, it does not belong in the main forecast. Accruals and non-cash items can live in a separate note if needed.
How do you estimate weekly customer receipts?
This is usually the hardest and most important part. Start with what you already know and get more conservative the further out you go.
- Pull the current accounts receivable aging report.
- List every open invoice with its due date.
- Adjust for real payment behaviour. If the customer is consistent with the delay of payment for 10 to 15 days, then you can put the bill slip 10 to 15 days after the due date.
- During weeks one to three, be specific: talk about the customer, the invoice, and which week it should happen.
- For weeks 4–13, use percentages based on history. Example: 70% of the 1–30 day bucket usually comes in within the next two weeks, 40% of the 31–60 day bucket, and so on.
New sales that have not been invoiced yet should be treated carefully. Only include them if you have a strong reason to believe the cash will arrive inside the 13 weeks. Many teams keep a separate “pipeline” line and only move amounts into the main forecast once an invoice is issued or a deposit is confirmed.
Over-confidence is the biggest mistake one could make. It is always better to under-estimate your revenue and then get a pleasant surprise than to over-estimate the revenue.
How do you schedule payroll, bills, and debt payments?
These are usually the most reliable lines, so give them your attention.
- Payroll: Write down specific dates along with gross payroll amount (taxes and benefits as well through the payroll system).
- Payable regular bills: Rent, software subscription, insurance, utilities, depending upon specific payable dates for them.
- Payment to suppliers: Start with payable bills and their specific dates. Then, calculate the actual payment made to each supplier per week considering your cash flow position and importance of suppliers.
- Payment of debt: Payment of principal amount along with the interest payment based on the specific due dates. Do not miss those dates.
- Tax payment: Tax deposits through payroll system, VAT/GST, installment payments of tax.
Tip: Prepare two lists per week – one of ‘must-pay’ lines (payroll, important suppliers, debts, taxes), and one of ‘flexible’ lines. In times of cash shortage, the ‘must-pay’ items are retained, while the others are reduced.
How do opening and closing cash balances connect?
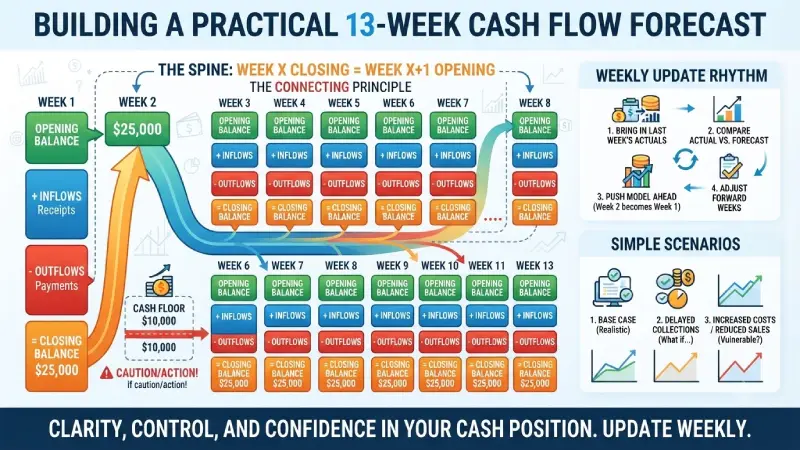
This is the spine of the whole forecast.
Week 1 opening balance = today’s actual bank balance (or the balance you expect at the start of the first forecast week).
Week 1 closing balance = Week 1 opening + Week 1 inflows – Week 1 outflows.
Week 2 opening balance = Week 1 closing balance.
And so on through Week 13.
The end of balance from one week becomes the starting point of balance for the next. It is this one simple connection that transforms a mere series of numbers into a running record of your cash runway.
Another parameter used by many companies is the cash floor. The cash floor is the minimum level of balance that a company will be comfortable working with. When the forecast indicates a balance that falls below this level, action must be taken immediately.
How do scenarios and weekly updates improve the forecast?
A static forecast loses value quickly. The power comes from two habits: updating it every week and running simple scenarios.
Weekly update rhythm
- Bring in last week’s actual receipts and payments.
- Comparison between Forecasting and Actual Results – Main Differences
- Push the model ahead such that last week’s Week 2 is now the new Week 1, and there is a new Week 13.
- Adjust the forward weeks based on what you learned.
This process usually takes 30–60 minutes once the model is set up. The goal is not perfection. It is to keep the picture current.
Simple scenarios
You do not need complicated models. Three versions are often enough:
- Base case (your best realistic view)
- Delayed collections (what if key customers pay 10–14 days later)
- Increased costs or reduced sales (what if a major cost occurs sooner or a revenue is delayed)
A quick comparison of the 13 weeks under other assumptions makes the areas of vulnerability very clear.
Accuracy gets better through experience. Teams usually strive to achieve ±5-10% accuracy for near weeks and more lenient margins as weeks go by. The key thing is to compare what was forecast to the actual and make a decision.
Putting the 13-week plan to work
Start simple. Open a spreadsheet, put the next 13 weeks across the top, and list the main cash categories down the side. Fill in what you know. Update it every week. After a month you will already see patterns that were invisible before.
The 13-week cash flow forecast is not glamorous. It is practical. It turns “I think we should be okay” into “here is exactly which weeks look tight and what we can do about them.” That clarity is usually worth far more than the time it takes to maintain.
FAQs on Cash Flow Forecasts
Why 13 weeks and not a full year or just one month?
Thirteen weeks represents one quarter of time. A monthly perspective obscures the week-to-week issues which are responsible for cash shortages. A yearly prediction may be valuable for planning, but it is too uncertain for decision-making. Thirteen weeks provide enough time to identify the potential problems, but not much time for unrealistic forecasts.
How accurate does the forecast need to be?
Near weeks (1–3) should be reasonably tight — many teams aim for within 5–10% on total cash movement. Further weeks can be more directional. What matters most is that you update it every week and learn from the differences between forecast and actual. Perfect accuracy is not the goal; early visibility is.
Should I capture all the little payments or should it be high level?
Firstly, get the big things that affect your cash flow: salaries, important vendors, important customers’ collections, rents, tax payments, and debt repayments. If you need to, you will get into further detail later. A basic but updated weekly model is far more useful than a complicated but outdated one.
What is the common mistake people do when developing 13 weeks forecasts?
Being overly optimistic about customer receipts. Putting the money in the week where the invoice is due and not in the week you get paid is by far the most frequent mistake. Use historical information and not the term of the invoice. Second mistake would be to prepare it once and then never update it.
How long does it take to build and maintain one?
Preparation of the first forecast generally takes a few hours if you have some clean receivable and payable information. Maintenance of the forecast after that generally takes 30-60 minutes per week.
Conclusion
An example of an analysis would be the creation of a cash flow forecast for 13 weeks. It would be simply a projection of cash coming in and out each week during the upcoming quarter. The numbers need to be realistic, with the revenues based on customer behaviour, and the expenses carefully scheduled. Running two or three different scenarios during tough times is enough. It will provide visibility instead of uncertainty.