Interest Rates on Business Loans The interest rate on the business loan is the additional amount which needs to be paid alongside the borrowed money, and in 2026 too, which will be ten years from now, there will be different interest rates for loans depending upon various factors such as the lender, borrower’s profile, type of loan, and fixed or floating interest rate.
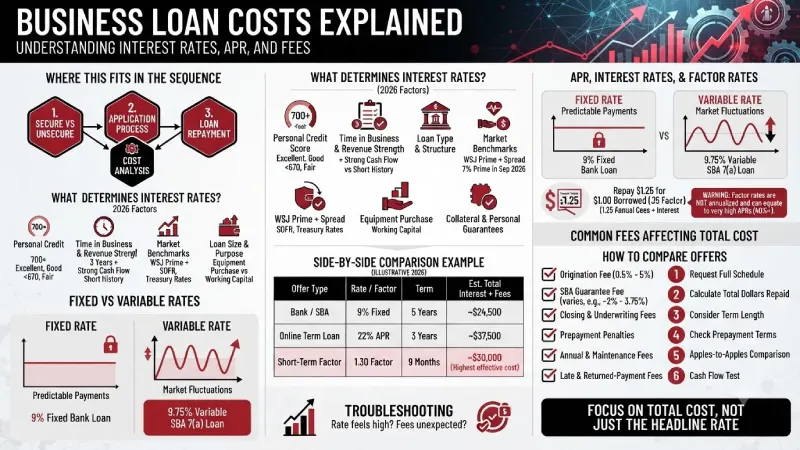
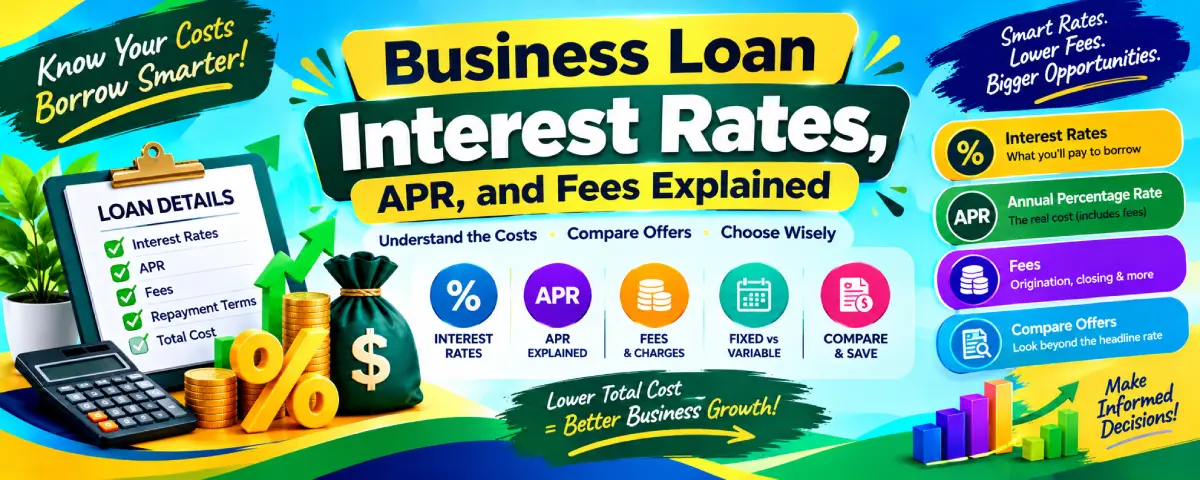
After going through the “Business Loans” pillar and the subsequent pages discussing types and requirements of a business loan, this guide will cover the factors determining interest rates, difference between fixed and variable rates, actual meaning of APR and factor rates, additional fees, and comparison of offers.
Where This Fits in the Sequence
You are familiar with the various kinds of loans and the general qualifications for them. What is left to look at now is the cost of such loans. The natural course of action here would be: You are familiar with the various kinds of loans and the general qualifications for them. What is left to look at now is the cost of such loans. The natural course of action here would be:
- Decide whether a secured or unsecured structure makes sense → Secured vs Unsecured Business Loans
- Walk through the application process → How to Apply for a Business Loan
- Plan how you will repay the loan → Business Loan Repayment
This keeps the information continuous and practical.
What Determines a Business Loan Interest Rate?
Lenders set rates by estimating risk and then adding a margin. Several factors consistently influence the number you are offered in 2026.
- Your credit profile
Personal credit scores of the owners (especially those with 20% or more equity) remain one of the strongest drivers. Banks and SBA lenders typically reserve their best rates for scores of 700+. Scores in the 670–699 range are often workable but at higher pricing. Online lenders stretch further down the credit spectrum, yet the rate climbs as the score drops. Business credit files also matter more as the company grows.
- Time in business and revenue strength
Longer operating history and consistent, higher revenue lower perceived risk. A business with three clean years and strong monthly deposits usually receives better pricing than one with nine months of history and uneven cash flow, even if the personal credit scores look similar.
- Loan type and structure
Term loans from banks and the SBA are among the lowest in the market. Term loans online, merchant cash advances, and certain line of credits are higher due to the additional risk being taken or for quicker availability of funds. Secured loans (with collateral) are usually priced lower than unsecured loans of the same size and term.
- Market benchmarks
Most business variable-rate loans are based on the Wall Street Journal Prime Rate (which was 7% as of September 2026) or other indices such as SOFR or Treasury rates. SBA 7(a) loans are based on prime plus a spread that is capped according to loan amounts. Fixed-rate loans are usually based on Treasury rates or the bank’s cost of funds.
- Loan size, term, and purpose
Larger loans and longer terms can sometimes receive slightly better pricing because the lender’s fixed costs are spread over more dollars and more months. Conversely, very small loans often carry higher relative rates. The stated purpose also matters—equipment purchases or real-estate-backed loans frequently receive more favorable treatment than pure working-capital requests.
- Collateral and personal guarantees
Where the borrower has a clear way out if anything happens, chances are that the rate will be improved. Hard collateral on top of a good personal guarantee is what is always required for most business loans.
It is possible for two owners with similar credit to get vastly different interest rates based simply on the strength of their income flow, time, and collateral.
How Do Fixed and Variable Rates Differ?
- Fixed rates
The interest rate stays the same for the entire term (or for a defined period). Your monthly payment remains predictable. This is useful for budgeting, especially if you expect interest rates in the broader economy to rise. The trade-off is that fixed rates often start a bit higher than the variable rate available on the same day, because the lender is taking the risk that market rates will move.
- Variable rates
The rate can change over the life of the loan, usually tied to an index such as prime. When the index rises, your rate and payment can increase; when the index falls, they can decrease. Many SBA 7(a) loans and bank lines of credit use variable pricing. The starting rate is often lower than a comparable fixed rate, but you accept payment uncertainty.
Practical comparison in 2026
With prime near 7%, a variable SBA 7(a) loan might start in the 9.75%–13.5% range depending on size and the lender’s spread. A fixed-rate version of a similar loan might start a point or two higher. Bank term loans can be offered either way. Online lenders more commonly quote fixed factor rates or fixed APRs for short-term products.
Use fixed if having the certain payments is more important than having the lower possible rate. Use variable if you think that interest rates will either decrease or remain constant, or if having a lower initial rate makes a significant difference to your cash flows.
How Do APR, Interest Rates, and Factor Rates Differ?
These three figures cannot be interchanged, and confusing them will make it easy for you to understate the true cost.
- Interest rate
The interest rate is the basic yearly cost of money in terms of a percentage. For a fully amortized loan, this is the interest rate used to determine the interest payments on each installment. This is not always inclusive of all costs.
- APR (Annual Percentage Rate)
The APR is meant to give an indication of the full cost of borrowing money in a year, inclusive of certain costs such as origination costs. The purpose of this is to ease comparison. A loan that has a 10% interest rate and a 3% origination cost will have a higher APR than another loan having a 10% interest rate and without an origination cost. Always ask for the APR where available, but consider the total cost and installment plan.
- Factor Rate
Commonly used in merchant cash advances and short-term online loans. The factor rate 1.25 means that you repay $1.25 for each dollar borrowed. Thus, for a loan advance of $50,000 with a factor rate of 1.25, you will repay $62,500. Factor rates are not annualized like interest rates and APRs and hence the 1.25 factor on a six-month product is much more expensive than a 12% APR in a multi-year term loan. You should convert the factor rate into an APR or the total dollar repayment
- Quick insight into factor rate conversion
Even a seemingly low factor rate in a short-term lending product can equate to an APR of 40%, 60%, or even more after annualization. Be sure to compare based on the repayment amount in dollars, not the amortization loan.
Which Fees Affect Total Borrowing Costs?
Charges may cost several thousand dollars and thus could make a more substantial difference than a slight change in rates.
Common fees in 2026
- Origination or packaging fee — typically 0.5%–5% of the loan amount, charged at closing. Some lenders deduct it from the funded amount.
- SBA guarantee fee — for 7(a) loans with terms over 12 months, the FY2026 schedule runs roughly 2% of the guaranteed portion on smaller loans up to 3.5%–3.75% on larger ones. This fee is usually passed through to the borrower.
- Closing, underwriting, or administrative fees — flat or percentage-based charges that vary by lender.
- Appraisal, environmental, or legal fees — more common on real-estate or larger secured loans.
- Prepayment penalties or fees — some term loans include an interest charge on the outstanding balance for paying early. Some offer free prepayment.
- Annual or maintenance fees — more common on lines of credit.
- Late fees and returned-payment fees — standard on most products; avoid them by setting up automatic payments when possible.
A loan with a slightly high interest rate but without any fees can prove to be more economical than a loan with a lower interest rate but heavy fees. Always ask for a full list of fees and an amortization schedule with the total of interest and fees.
How Can You Compare Repayment Schedules and Offers?
Looking only at the monthly payment or the headline rate is incomplete. Use these practical steps.
- Request the full amortization or repayment schedule
See what percentage of each installment is applied towards the interest and principal respectively, and what will be the total interest payable over the entire tenure.. - Calculate total dollars repaid
Principal + total interest + all fees = true cost. Compare this number across offers of similar size and purpose. - Look at the term length
A longer term lowers the monthly payment but usually increases total interest. A shorter term raises the monthly payment but reduces total interest. Match the term to how long the benefit of the funds will last. - Check prepayment terms
If you expect to refinance or pay early, a loan with no or low prepayment penalty is more valuable. - Compare apples to apples
A loan for 36 months with 25% annual interest rate online does not compare to an SBA loan at 11% interest rate over a period of 7 years. Put all figures into monetary terms and its effect on cash flows. - Run a simple cash-flow test
From the net monthly cash flow, subtract the loan installment. You should make some allowance for error (usually 20-30%). If the installment leaves little room left in the margin of error, then you have an overaggressive loan offer. - Side-by-side comparison example (illustrative 2026 numbers)
Assume you need $100,000:
| Offer Type | Rate / Factor | Term | Approx. Monthly Payment | Est. Total Interest + Fees | Notes |
| Bank / strong SBA | 9% fixed | 5 years | ~$2,075 | ~$24,500 | Lower total cost, longer process |
| Online term loan | 22% APR | 3 years | ~$3,820 | ~$37,500 | Faster funding |
| Short-term factor | 1.30 factor | 9 months | Daily/weekly draws | ~$30,000 | Highest effective cost |
These are simplified examples. Your actual offers will differ. The table shows why total cost and cash-flow fit matter more than any single number.
2026 Rate Snapshot Tables
Typical rate ranges by product (approximate)
| Product | Typical Rate / Cost Range | Common Benchmark |
| Bank small-business term | 6.4% – 11% | Prime or internal |
| SBA 7(a) variable | ~9.75% – 13.5% | Prime + capped spread |
| SBA 7(a) fixed | ~11% – 15% | SBA peg / Treasury-based |
| SBA 504 | 5% – 7% | Treasury + fees |
| Online term loan | 14% – 99% APR | Risk-based |
| Business line of credit | 7% – 99% APR | Prime or risk-based |
| Equipment financing | 4% – 45% APR | Asset + credit |
| Invoice factoring | 1% – 5% fee per period | Invoice quality |
| Merchant cash advance | 1.10 – 1.50 factor | Revenue-based |
SBA 7(a) maximum spreads (illustrative with ~7% prime)
Loan size affects the maximum allowable rate. Larger loans have lower maximum spreads, which is why bigger SBA loans often price more attractively.
Frequently Asked Questions
What should be a good interest rate for a business loan in 2026?
Less than 10-11% for traditional loans from a bank or SBA, while online loans have higher interest rates by their nature. Concentrate on the total cost instead of just the lowest one.
Is APR always more than the interest rate?
Normally, yes, because APR includes some fees. Without fees, both values will be the same.
Should I always look for the lowest rate?
No, you may prefer a somewhat higher rate, which does not have the prepayment penalty, or fits better your cash flow, or provides faster funds.
Will the rates go up or down after my loan approval?
Fixed rates do not change. Variable ones might depend on the index value. Some online loans lock in the rate after loan approval, other may change until funds are disbursed.
How do I lower the rate I am offered?
Make your credit score better, demonstrate strong income levels that are consistent, provide collateral, lower the amount of money you want to borrow, or increase the term a little bit if possible. Comparing several banks is beneficial.
Troubleshooting Cost-Related Problems
The rate feels high compared with online articles
Articles show ranges. Your rate reflects your specific credit, time in business, revenue, and the lender’s risk appetite. Improve the file or add collateral if possible.
Fees are higher than expected
Ask for a full fee breakdown in writing. Some costs are flexible while others (like SBA guarantee costs) are fixed by the program. Compute the effect on total cost before making the decision.
Variable rate makes you nervous
Choose a fixed-rate product if payment certainty is more important than the lowest starting rate. Or take a variable rate with a shorter term so the exposure is limited.
Two offers look similar but total cost differs
Compare total dollars repaid and the payment schedule side by side. The offer with the lower monthly payment is not always the cheaper one over the full life of the loan.
Conclusion
Comprehension of business loan interest rates, APR and fee structures will allow you to move beyond the figures presented by marketing to see what you are really paying. Using the information provided above regarding interest rates, APR, and fees, as well as the examples provided in tables, you can proceed on to the next cluster pages on whether a particular financing choice is a secure one or an unsecure one, applications and payment schedules.