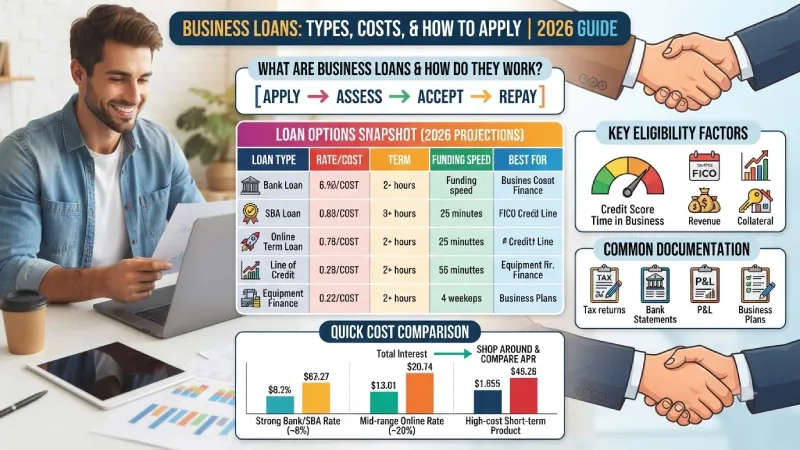
The business loan is a financial resource that enables the entrepreneur to raise money required to grow, fix gaps, buy equipment, or capitalize on an opportunity without touching his/her bank savings. With prime interest rates projected at 7% for the year 2026 and small business loan interest rates for banks being from 6.4% to 11%, the proper loan will be the determining factor that determines success or stagnation. The purpose of this article is to cover all the basics.
What Are Business Loans and How Do They Work?
A business loan is the money lent by the lender to your business, which you pay back over time with interest. The difference between a business and a personal loan is that the money is meant to be used for business needs such as inventory, equipment, staffing, growth, marketing, or cash flow.
Here’s the simple flow most loans follow:
- You apply for the loan and provide financial information.
- The lending institution assesses your credit score, earnings, business tenure, and, in some cases, even assets.
- If accepted, you are provided with a one-time loan amount or a revolving line of credit.
- You repay with periodic payments covering both the principal and interest.
- Upon paying off the loan, the loan cycle ends.
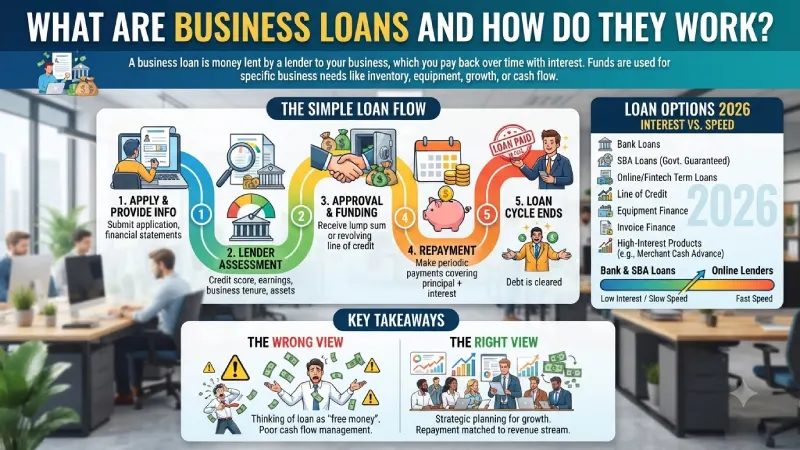
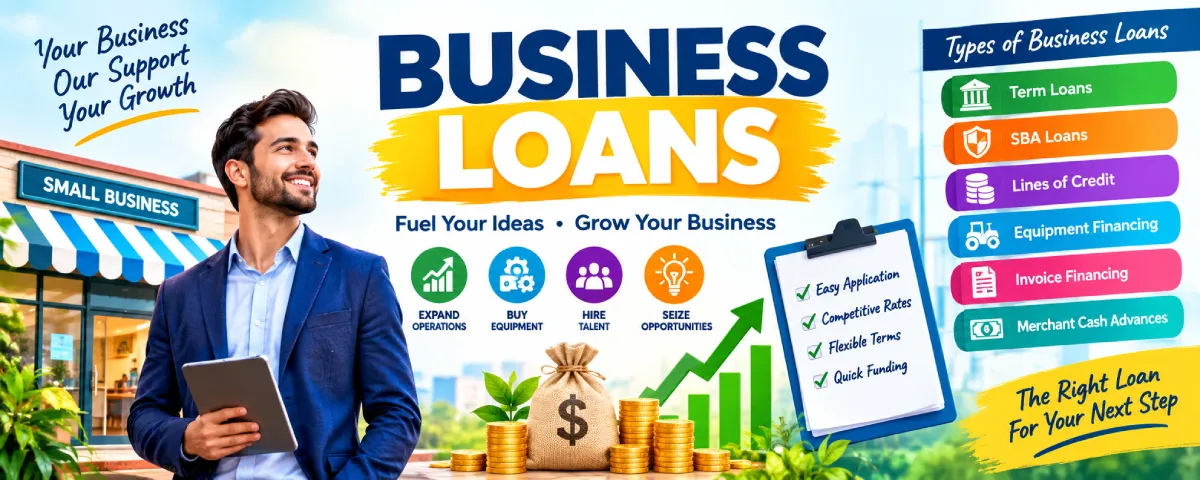
Loans provided in the year 2026 include bank loans, SBA loans which are guaranteed by the government, term loans from the internet and fintech companies, line of credit, equipment finance, invoice finance, and some high-interest products including merchant cash advance. Bank and SBA lenders provide the lowest interest rate but take the longest time while online lending institutions provide loans fast but at a higher interest rate.
I have encountered cases where loan recipients think of loans as free money and end up suffering due to poor cash flow management. The successful individuals view the loans as a means of achieving something that has been planned out and with a repayment method that matches their revenue stream. This all begins with the product knowledge.
Key terms you’ll see repeatedly:
- Principal — the amount you borrow.
- Interest rate — the cost of borrowing, usually expressed as an annual percentage.
- APR — annual percentage rate that includes interest plus certain fees for a truer cost comparison.
- Term — how long you have to repay (months or years).
- Collateral — assets the lender can claim if you default.
- Personal guarantee — your personal promise to repay if the business cannot.
- Debt-service coverage ratio (DSCR) — This is used to gauge whether the additional payments can comfortably fit into your cash flow (usually 1.15x-1.25x or more).
Which Types of Business Loans Are Available?
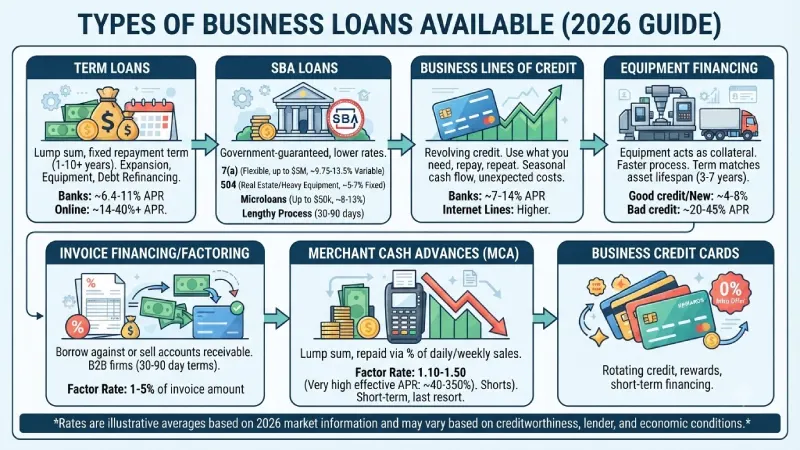
Not every loan fits every need. A match between the product and the intended use will save you time and trouble. These are the primary categories that are relevant in 2026, with average price ranges based on existing market information.
- Term loans
A lump-sum amount is provided and paid back in monthly installments within an agreed-upon period (usually from 1 to 10 years for regular loans, while for SBA – longer). Ideal choice for one-time requirements like expansion, equipment, or debt refinancing at better rates than previous financing. Term loans from banks range around 6.4% to 11% annually for eligible customers. Online term loans are more expensive, about 14% to 40%+ annually.
- SBA loans
Such loans are provided by banks or any other lenders but guaranteed in part by the Small Business Administration, U.S. The partial guarantee reduces the risks of the lender, which often results in lower interest rates for the customer..
- 7(a) — the most flexible; can be used for almost any legitimate business purpose up to $5 million. Variable rates are typically capped near prime + 3%–6.5% (so roughly 9.75%–13.5% with a 7% prime). Fixed rates sit a bit higher.
- 504 — designed for fixed assets such as real estate or heavy equipment; rates often land in the 5%–7% range with long terms (10–25 years).
- Microloans: up to $50,000 via non-profit intermediary agencies; usually 8-13%.
SBA loan processing is lengthy (30-90 days) and involves a lot of paperwork, however; these continue to be some of the cheapest sources available for those qualified.
- Lines of credit for business
This is a revolving line of credit just like the credit cards. You use what you need, pay for the interest of the borrowed amount and repay. This is ideal when dealing with seasonal cash flow problems or any other kind of unexpected cost. Interest rates on bank lines will be around 7%-14% while internet lines may be higher.
- Equipment financing or equipment loans
In this case, the equipment will act as the collateral. Interest rates here begin at 4%-8% for good credit and new equipment going up to 20%-45% for bad credit files. The duration of the loan will correspond to the life span of the asset which is 3-7 years. The process is faster than a general term loan due to clear collateral.
- Invoice financing or factoring
This is where you factor your accounts receivable either through selling or borrowing from the invoices. The rate of factoring will be between 1%-5% of the invoice amount. It is suitable for a B2B firm that waits for 30-90 days to receive payments.
- Merchant cash advances (MCAs)
You receive a lump sum and repay via a percentage of daily or weekly card sales (or bank deposits). Factor rates of 1.10–1.50 are common, which can translate to very high effective APRs (sometimes 40%–350%). These are fast but expensive and best treated as short-term last-resort capital.
- Business credit cards
Rotating credit with rewards or 0% introductory offers. Interest rates beyond the promotional period tend to range from the upper teens to low 20s. Very suitable for smaller transactions but not for larger amounts of capital.
Comparison – Typical 2026 Ranges (Approximate)
| Loan Type | Typical Rate / Cost | Loan Amounts | Term | Funding Speed | Best For |
| Bank term loan | 6.4%–11% | $25k–$1M+ | 1–10 years | 2–8 weeks | Established businesses, expansion |
| SBA 7(a) | ~9.75%–13.5% variable | Up to $5M | Up to 10–25 years | 30–90 days | Flexible use, lower long-term cost |
| SBA 504 | 5%–7% | $125k–$5.5M | 10–25 years | 60–90+ days | Real estate / large equipment |
| Online term loan | 14%–99% APR | $5k–$500k | 3 months–5 years | 1–7 days | Speed, less-than-perfect credit |
| Business line of credit | 7%–99% APR | $10k–$250k+ | Revolving | Same day–2 weeks | Cash-flow flexibility |
| Equipment financing | 4%–45% APR | Cost of equipment | 2–7 years | 3–14 days | Specific asset purchases |
| Invoice factoring | 1%–5% fee | Based on invoices | Per invoice | 1–3 days | B2B with slow-paying customers |
| Merchant cash advance | 1.10–1.50 factor | $5k–$500k | 3–18 months | 1–3 days | Very fast capital (high cost) |
These ranges vary depending on credit history, collateral, and market trends. Make sure you document all of them in written form, and also check for the total repayment cost.
What Affects Business Loan Eligibility and Approval?
Here are some key factors to consider. It will be useful for preparing your loan application.
Personal and business credit
The majority of banks and SBA lending institutions prefer FICO scores ranging from 670 to 680 or higher, while the lowest interest rates will be achieved by those with 700+ scores and above. The online lenders and niche lenders may also take into account FICO scores between 550 and 600, and some of the revenue based financing will even consider scores in the 500s if bank deposits are good.
- Time in business
Traditional banks and even SBA preferred lenders require at least 2 years. Online lenders and equipment financing institutions tend to accept from 6 months to one year. Start-ups have fewer choices and generally have to offer higher interest rates.
- Revenue and cash flow
Annual revenue of $100,000+ is a common floor for many term loans and lines. Some online lenders look at monthly deposits ($10k–$25k+). Lenders also examine consistency—frequent overdrafts or large swings raise red flags. DSCR calculations show whether projected cash flow can cover the new debt service with a cushion.
- Collateral and personal guarantees
Collateralized loans involve some sort of asset (equipment, property, inventory, accounts receivable). Unsecured loans involve more credit and cash flow considerations but will always have some sort of guarantee involving the owners who hold at least 20% ownership. Even SBA loans usually involve a guarantee and sometimes collateral.
- Industry, use of funds, and documentation
Some industries are viewed as higher risk. Clear, legitimate use of proceeds helps. Clean, organized paperwork—tax returns, bank statements, P&L, balance sheet, debt schedule—speeds underwriting and signals professionalism.
Common 2026 documentation checklist
- Business and personal tax returns (1–3 years)
- Business bank statements (3–12 months)
- Year-to-date profit & loss and balance sheet
- Debt schedule listing existing obligations
- Business formation documents and EIN
- Personal financial statement for guarantors
- Business plan or funding details (particularly for larger or SBA loans)
In most instances, I have seen fantastic companies being overlooked because of bad paperwork. This is perhaps one of the best methods through which you can cut down costs before applying.
How Do Interest Rates, Fees, and Collateral Compare?
Interest is only one aspect of the cost. Changes in fees, repayment schedules, and the need for collateral affect the true cost and risk involved.
Interest rates in 2026
Bank and SBA loans remain the lowest-cost options for qualified borrowers. Online products trade higher rates for speed and flexibility. Variable rates move with the prime rate (currently around 7%); fixed rates give payment certainty. Always compare APR when possible, and ask for a full amortization schedule so you can see total interest over the life of the loan.
Common fees
- Origination/packaging fees (0.5%-5% of the loan amount)
- SBA guaranty fees (for SBA 7(a) loans exceeding 12 months: 2%-3.75% of the guarantied amount depending on the size, as per FY2026 schedule)
- Closing/appraisal/underwriting fees
- Prepayment fees for some term loans
- Yearly/maintenance fees for lines of credit
Sometimes it is better to have a marginally higher interest rate than a lower one if the latter comes with higher fees.
Collateral impact
Secured loans have a tendency to be cheaper and larger since the lender has a way of getting their money back. Unsecured loans will have high costs and also a cap on their limit. Equipment financing will be a hybrid since it uses the asset as collateral for the loan.
Quick cost comparison example
Assume a $100,000 need repaid over 5 years:
- Strong bank/SBA rate ~8% → roughly $2,028 monthly payment, total interest ~$21,700
- Mid-range online rate ~20% → roughly $2,649 monthly, total interest ~$58,900
- Higher-cost short-term product can easily double or triple the interest cost
These are illustrative only; your actual offers will depend on your file. The gap shows why shopping and improving your qualifications before applying matters.
How Do You Apply and Plan Loan Repayments?
Application process (practical sequence)
- Define the exact purpose and amount. Be specific—lenders dislike vague “working capital” requests.
- Check your credit, sales, and time-in-business against normal requirements.
- Gather documents early.
- Compare 3–5 lenders or use a marketplace that matches you without excessive hard pulls.
- Submit complete applications. Incomplete files slow everything.
- Carefully review the offer: rating, fee, term, pre-payment, collateral, and personal guarantee.
- Accept, close, and put the funds to the stated use.
Funding timelines range from 24–48 hours (some online products) to 60–90 days (many SBA loans). Plan accordingly.
Repayment planning
Work the payments into your cash-flow projections before making an agreement. An amortization table will demonstrate how much is allocated to interest payments initially. Daily or weekly payment structures (popular with certain types of online and MCA products) can put more pressure on your cash flow compared to monthly payments. While paying off a loan early will reduce interest, there might be penalties for doing so—so make sure to read the terms.
Consider building a buffer zone of 20–30%. Your monthly payments should ideally leave room for such a buffer zone in your cash flow. Treat the debt as another major expense that needs to be kept an eye on.
Practical Tips from Experience
- Work to improve your credit and straighten out your bank statements at least 3-6 months in advance of applying.
- Be prepared with an explanation of how you plan to use the money.
- Do not make applications to numerous lenders; it may adversely affect you.
- Perhaps start small and gradually grow larger.
- Get some input from an accountant regarding how the loan will affect your taxes and balance sheet.
- Read everything that is written in the loan agreement. Questions regarding collateral, default, and prepayments are legitimate.
Frequently Asked Questions
What credit score do I need for a business loan in 2026?
Banks and most SBA lenders prefer 670–680+. Online lenders often accept 550–600. Some revenue-based products go lower when deposits are strong.
How long does approval take?
Online products: days. Bank term loans: weeks. SBA: often 30–90 days.
Do I need collateral?
Not always. Smaller SBA loans and many unsecured online products do not require specific collateral, though personal guarantees are common.
Can startups get business loans?
Yes, but options are more limited and usually more expensive. Equipment financing, microloans, and some online products are more accessible than traditional bank or standard SBA loans.
What is a good interest rate right now?
Under 10–11% for bank or SBA term loans is competitive for strong files. Online rates are higher by design.
Should I choose fixed or variable rates?
Fixed gives payment certainty. Variable starts lower but can rise if the prime rate increases.
Troubleshooting Common Problems
Application denied
Question: What should be the next step?
Answer: Ask about the reason for rejection. Possible solutions include improving your credit score, reducing the amount asked for, pledging collateral, or waiting until you’ve been in business for longer.
Rates higher than expected
Browse different loaners, enhance your credit, or go for the secured approach. At times, a somewhat higher interest rate with improved conditions (zero prepayment penalties, longer maturity period) makes for a more favorable situation.
Financing pressure due to cash flow
Renegotiate if you can, restructure into a longer-term financing structure, or reduce unnecessary costs. If you think you will be in difficulty, contact your financier ahead of time because most would rather talk than have a default.
Too much paperwork for the SBA
Partner with a seasoned SBA preferred lender or SBA loan packaging specialist that understands the process. The majority of the documentation is stuff you should have on hand anyway.
Not sure what type of product to use
Refer back to the comparison chart and “Where to Start” above, and then look at the specific clusters.
Business loans are instruments rather than miracle solutions. Those entrepreneurs who succeed in using them properly know how to tailor the service to a specific need, comprehend the total cost, and ensure repayment is reasonable in terms of real income. Use the first pillar as a compass to navigate and go further through the cluster guides that provide more detailed instructions. Finally, when you are ready, do the math and make your choice.
Conclusion
Business loans are an extremely effective means as long as the borrower knows why and how he will be using them. While in 2026 the number of options is huge – from affordable loans issued by banks and SBA to quick online solutions – choosing a certain product depends on three factors: how the money will be used, how urgently it is needed and how easily the cash flow allows paying the sum back.
Successful borrowers regard the loan as an investment rather than a free money resource. They do the calculations based on total cost and not just the payment rate, gather the necessary documents and pick the right loan product in accordance with their real needs. Regardless of the kind of product – be it a term loan, line of credit, equipment or invoice financing or even an SBA loan – the idea is to use the money in order to make the business stronger without causing any extra stress.
Start from this general guide. Further, check the cluster articles which contain specific information about various loan products, their eligibility criteria, cost, application process, secured and unsecured loans, etc. When both product, cost and repayment terms suit the